Starting a business is exciting. Keeping track of every payment, invoice, receipt, subscription, bank transaction, and tax obligation usually isn’t.
But good bookkeeping is one of the habits that can make a startup easier to manage as it grows.
Clean financial records help you understand where your money is going, monitor profitability, prepare for taxes, catch mistakes early, and make more informed business decisions. They can also make conversations with accountants, lenders, investors, and other financial professionals much easier.
You don’t need an overly complicated accounting system on day one. What matters most is building a bookkeeping process that is accurate, consistent, and appropriate for your business.
Affiliate Disclosure: This article contains affiliate links. If you join Wealthy Affiliate through one of my links, I may earn a commission at no additional cost to you. I recommend only products and services I have personally used or genuinely believe will add value for my readers. All opinions expressed in this review are my own.

Here are 10 bookkeeping practices startups should establish as early as possible.
1. Choose the Right Accounting Method
One of your first bookkeeping decisions is how you record your business income and expenses.
The two primary approaches are cash-basis and accrual accounting.
Cash-Basis Accounting
Under cash-basis accounting, income is generally recorded when it is received and expenses when they are paid.
For example, if your consulting business sends a client an invoice in August but receives payment in September, you would generally record the income in September under the cash method.
This method can be easier for smaller businesses because it closely follows actual cash moving in and out of the business.
Accrual Accounting
Under accrual accounting, revenue is generally recognized when earned and expenses when incurred, rather thanwhen cash changes hands.
That can give a growing company a more complete picture of its financial activity, particularly when it has accounts receivable, accounts payable, inventory, subscriptions, or more complex transactions.
However, the right method isn’t simply a matter of preference. Tax rules, business structure, inventory, revenue level, contracts, and other circumstances can affect which accounting methods are available or appropriate.
If you’re unsure, discuss your setup with a qualified accountant or tax professional before deciding.
2. Separate Business and Personal Finances
One of the simplest ways to improve your bookkeeping is to create a clear boundary between business and personal money.
Use a dedicated business bank account for business income and expenses. A separate business credit card can make expense tracking even easier.
Instead of searching through months of personal transactions to determine which purchases were business related, you’ll have a much cleaner financial trail.
This makes it easier to:
- Reconcile your accounts
- Categorize expenses
- Review cash flow
- Prepare financial statements
- Provide documentation at tax time
Keeping finances separate is particularly important for business entities where maintaining a clear distinction between the business and its owners matters.
A separate account doesn’t automatically make an expense deductible, however. The underlying expense still needs to qualify under applicable tax rules.
3. Record Transactions Consistently
Don’t allow several months of transactions to pile up before updating your books.
The longer you wait, the easier it becomes to forget what a transaction was for, overlook an expense, duplicate an entry, or categorize something incorrectly.
For a small startup, weekly transaction reviews may be enough. Businesses with higher transaction volumes may benefit from more frequent bookkeeping.
Your records should capture important activity such as:
- Sales and other income
- Customer payments
- Vendor bills
- Operating expenses
- Credit card purchases
- Loan payments
- Owner contributions and distributions
- Payroll
- Refunds and chargebacks
The IRS states that businesses may use any recordkeeping system suitable for the business as long as it clearly shows income and expenses. Good records are also necessary to support amounts reported on tax returns.
Consistency matters more than building an unnecessarily complicated system.
4. Reconcile Bank and Credit Card Accounts Regularly
Recording transactions isn’t enough. You also need to verify that your bookkeeping records agree with what actually happened at the bank.
That’s where reconciliation comes in.
At least monthly, compare your bookkeeping records with your:
Bank accounts, business credit cards, payment processors, loan accounts, and other financial accounts.
If your books say your business has $18,000 in the bank, but your bank statement says $16,500, you need to know why.
The difference could be caused by something simple, such as an outstanding payment. But reconciliation can also uncover duplicate entries, missed transactions, bank fees, incorrect amounts, payment-processing discrepancies, or unauthorized activity.
Even if your accounting software automatically imports bank transactions, reconciliation still matters.
Automation can import information. It doesn’t guarantee that the information has been interpreted correctly.
5. Categorize Income and Expenses Consistently
A good chart of accounts should make your financial statements useful—not confusing.
For example, an ecommerce company might separately track:
Sales revenue, cost of goods sold, shipping expenses, merchant processing fees, advertising, software subscriptions, and returns.
A service business may need categories for:
Consulting revenue, subcontractors, software, professional fees, advertising, insurance, office expenses, and travel.
Avoid creating a new expense category every time you encounter something slightly different.
Consistent categories make it easier to compare months, identify trends, prepare financial reports, and work with your tax professional.
They can also reduce the risk of treating personal spending or nondeductible expenses as business deductions.
For federal income-tax purposes, deductible business expenses generally must be both ordinary and necessary for the business. Personal portions of mixed-use expenses generally aren’t deductible as business expenses.
6. Keep Organized Supporting Records
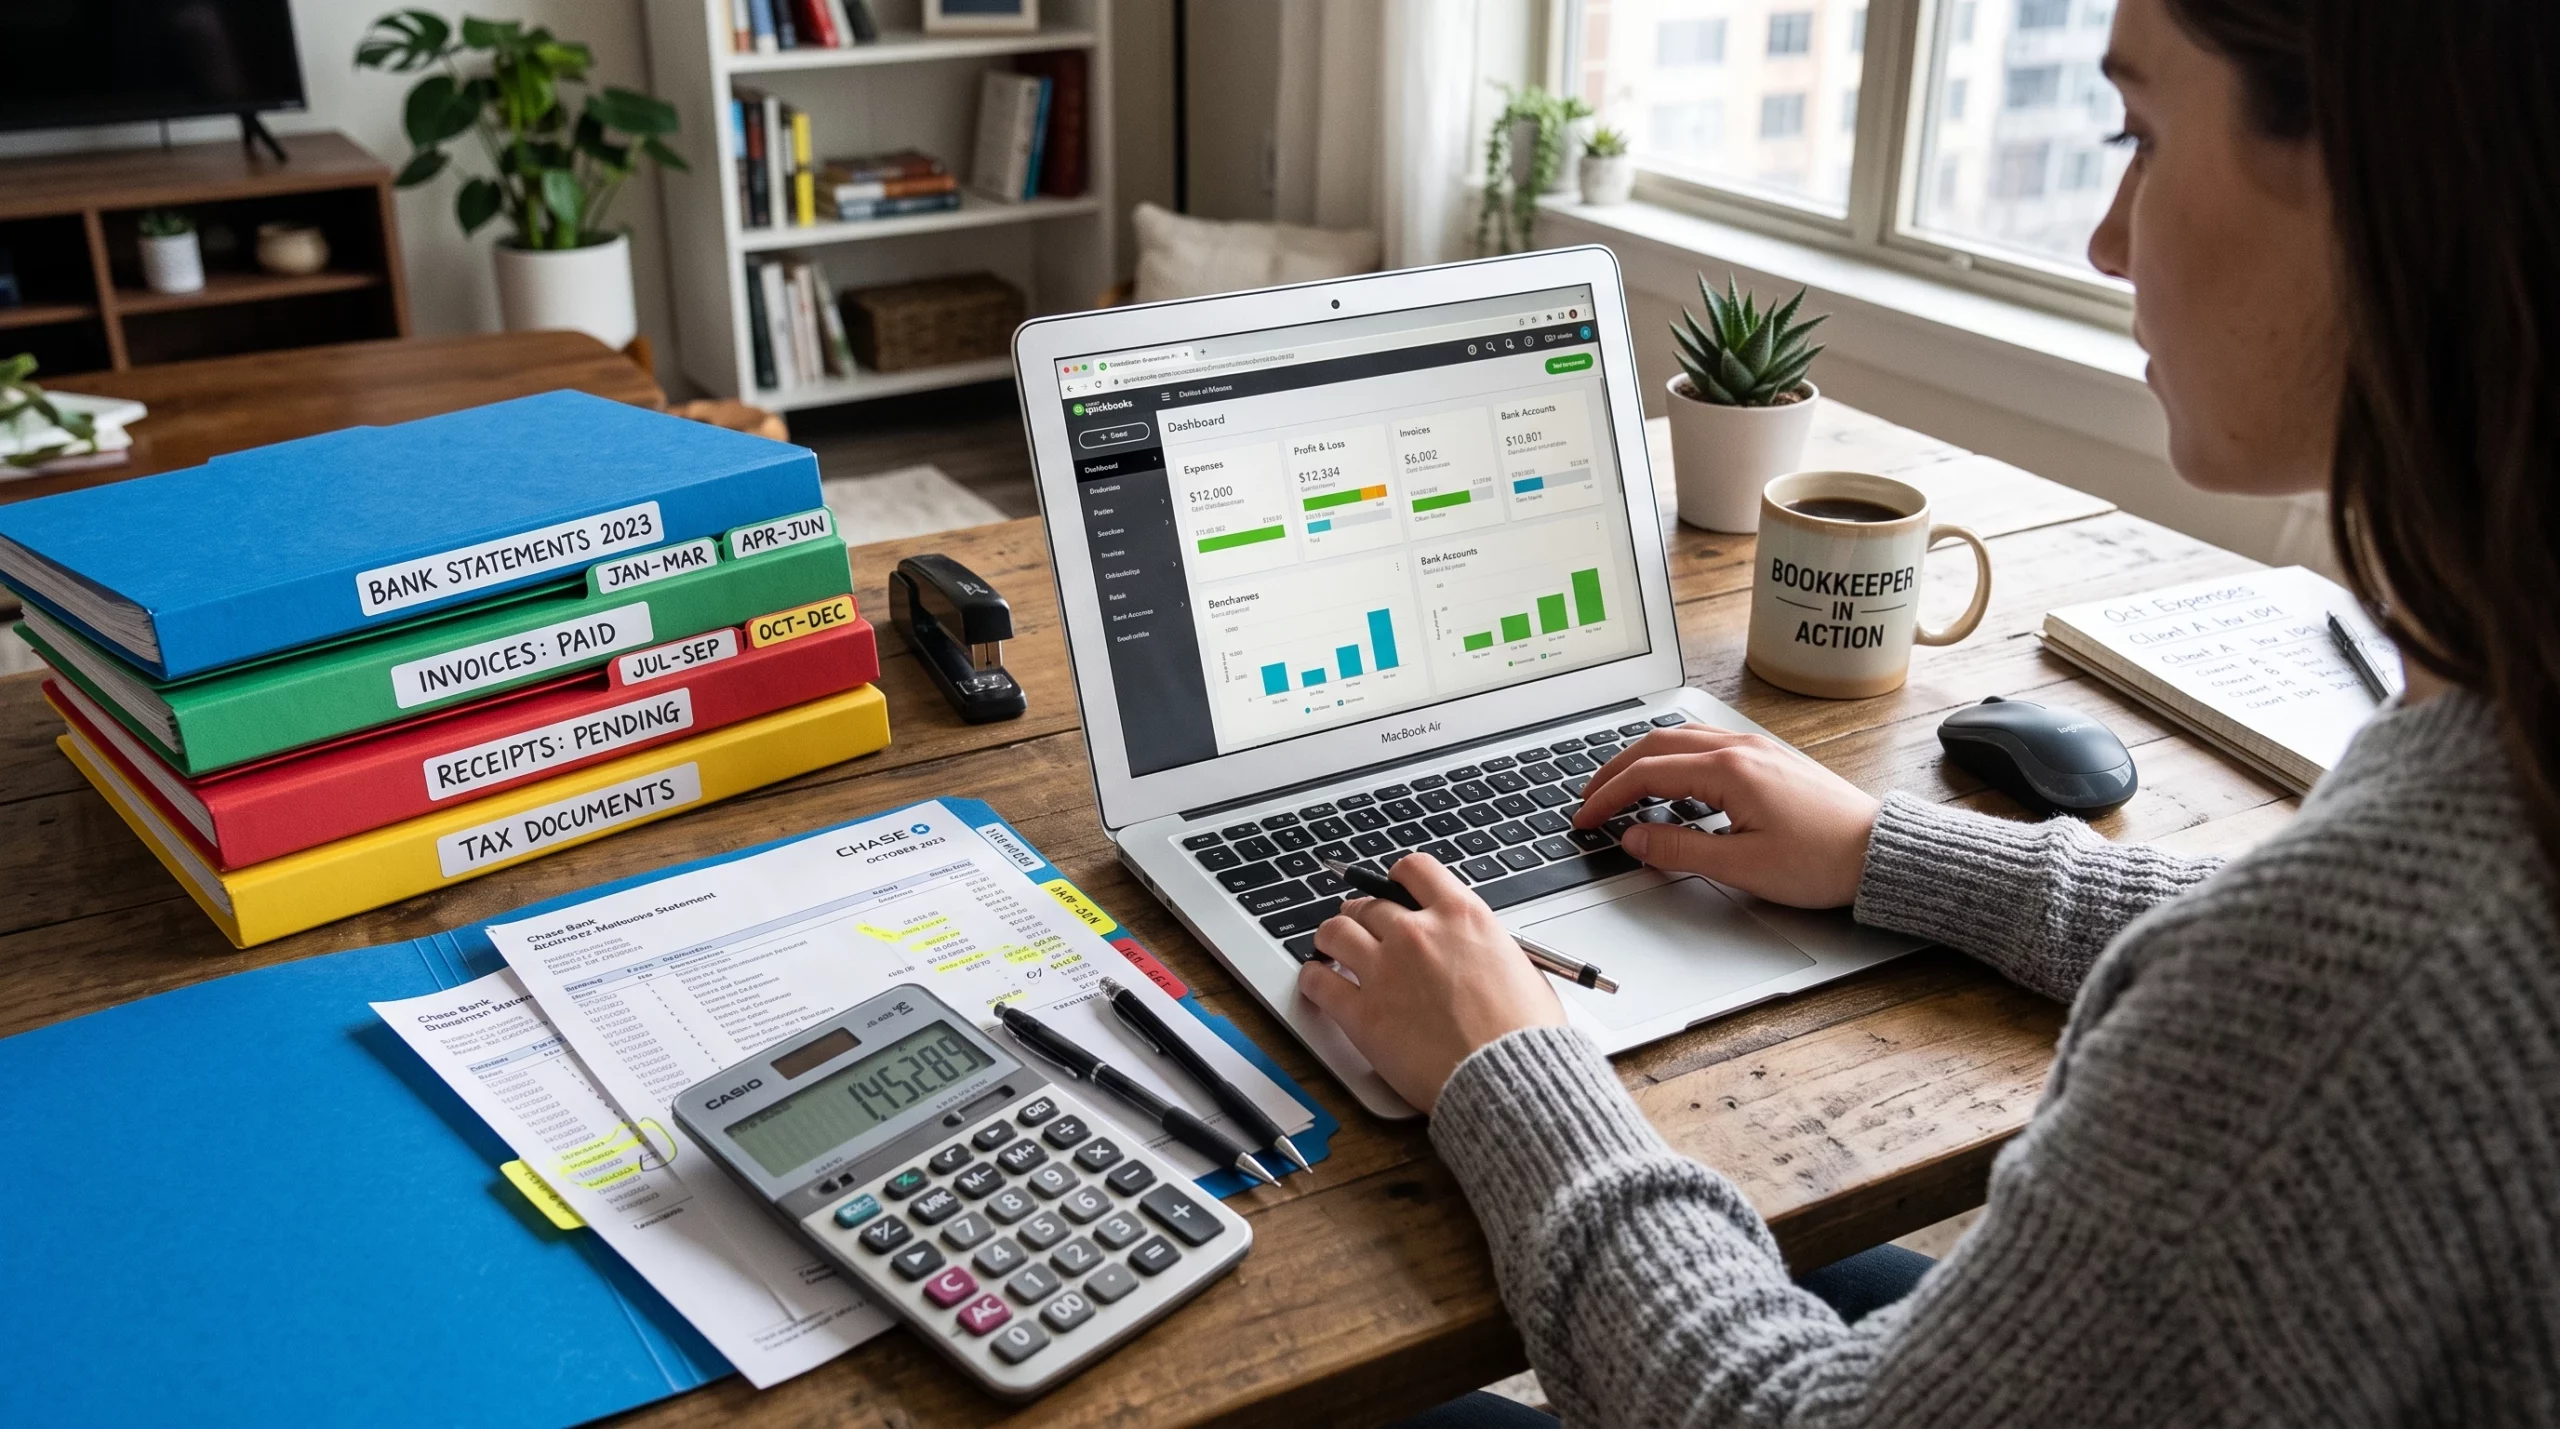
Your bookkeeping entries should be supported by documentation.
Depending on the transaction, this may include invoices, receipts, bills, deposit records, bank documentation, payment confirmations, contracts, payroll records, or credit card statements.
The IRS specifically identifies documents such as invoices, receipts, deposit information, canceled checks, and other proof of payment as common supporting records for businesses.
Digital records are perfectly practical when maintained properly. The key is to keep records accurate, organized, accessible, and tied to the transactions in your books.
Don’t rely on a universal rule such as “keep everything for seven years.”
Record-retention periods depend on the document type and the circumstances. Many federal income-tax records fall under a three-year limitation period, while other situations require longer retention. Employment-tax records, for example, generally should be kept for at least four years after the tax becomes due or is paid, whichever is later.
Property records may need to be retained until after the property is disposed of and the applicable limitation period has expired.
When in doubt, ask your tax professional how long specific records should be retained.
7. Review Your Financial Reports Every Month
Bookkeeping shouldn’t exist only to prepare your tax return.
Its real value is helping you understand your business.
At minimum, many startup owners should become familiar with three reports:
Profit and Loss Statement
Your profit and loss statement shows revenue, expenses, and profit or loss over a period of time.
Balance Sheet
Your balance sheet provides a snapshot of assets, liabilities, and equity.
Cash Flow Information
Cash-flow reporting helps you understand how money is entering and leaving the business.
Additional metrics will depend on your industry.
An ecommerce startup may monitor gross margin, inventory, returns, and advertising costs.
A subscription-based business may track recurring revenue, churn, acquisition costs, and customer retention.
A consulting business might watch billable revenue, outstanding invoices, contractor costs, and profit per client.
Don’t just generate reports—review them.
Ask what changed and why.
8. Automate Carefully
Modern bookkeeping software can eliminate a significant amount of repetitive work.
Bank feeds can import transactions. Receipt-capture tools can store supporting documents. Invoicing systems can send reminders. Ecommerce platforms can connect sales activity with accounting software.
Automation can save time, but it shouldn’t become “set it and forget it.”
Automated systems can still:
Misclassify expenses, create duplicate transactions, incorrectly match payments, mishandle transfers, or import incomplete information.
Think of automation as a bookkeeping assistant—not a replacement for review.
Use technology to handle repetitive tasks while keeping human oversight over categorization, reconciliation, reporting, and unusual transactions.
9. Plan for Taxes Throughout the Year
Tax planning shouldn’t start a few days before a return is due.
Your startup may have obligations involving federal income tax, state income tax, estimated tax payments, payroll taxes, sales and use taxes, franchise taxes, or other state and local requirements.
Which taxes apply depends on factors including your business structure, location, employees, activities, and where you sell.
Instead of randomly choosing one percentage of every sale and assuming it will cover everything, identify the taxes your business is actually responsible for and build a cash-reserve strategy around them.
Sales taxes collected from customers also need special attention because they generally represent amounts collected for a taxing authority rather than ordinary business revenue.
Keep tax-related liabilities organized separately in your bookkeeping system and review them regularly.
Working with a tax professional before year-end can also give you more time to correct problems and make informed planning decisions.
10. Know When to Bring in Professional Help
Many founders can handle basic bookkeeping when their businesses are small.
The question is whether they should continue doing it as the company becomes more complicated.
Professional help may become valuable when you begin dealing with growing transaction volume, payroll, multiple sales channels, inventory, loans, multiple states, contractors, complex tax requirements, or financial reporting for lenders and investors.
A bookkeeper can help keep day-to-day records organized and reconciled.
An accountant or tax professional can assist with more technical accounting, reporting, tax, and compliance questions.
You don’t necessarily need to outsource everything. The goal is to keep the financial side of the business from becoming a bottleneck—or an expensive cleanup project later.
Bonus Practice: Create a Monthly Bookkeeping Routine
The best bookkeeping system is the one you actually maintain.
Consider creating a simple monthly close routine.
Review uncategorized transactions. Reconcile financial accounts. Check outstanding invoices and bills. Review your profit and loss statement and balance sheet. Confirm payroll and tax liabilities. Investigate unusual transactions.
Then back up important records.
A predictable routine turns bookkeeping from a stressful year-end project into a normal part of running the business.
Strong Books Create a Stronger Foundation
Good startup bookkeeping is about much more than entering transactions.
It creates visibility.
When your records are accurate and up to date, you can see whether the business is profitable, where cash is going, which expenses are increasing, what customers owe you, what you owe others, and where potential problems may be developing.
Start simple.
Separate your finances. Record transactions consistently. Reconcile your accounts. Keep supporting documentation. Review your financial reports. Use automation wisely. And get professional help when your business becomes more complex.
Those habits can make everything from tax preparation to strategic planning easier as your startup grows.
Need help keeping your books organized?
IntegriBooks helps small businesses build cleaner bookkeeping processes and gain a clearer picture of their finances.
Explore IntegriBooks and take the next step toward cleaner, more reliable books.