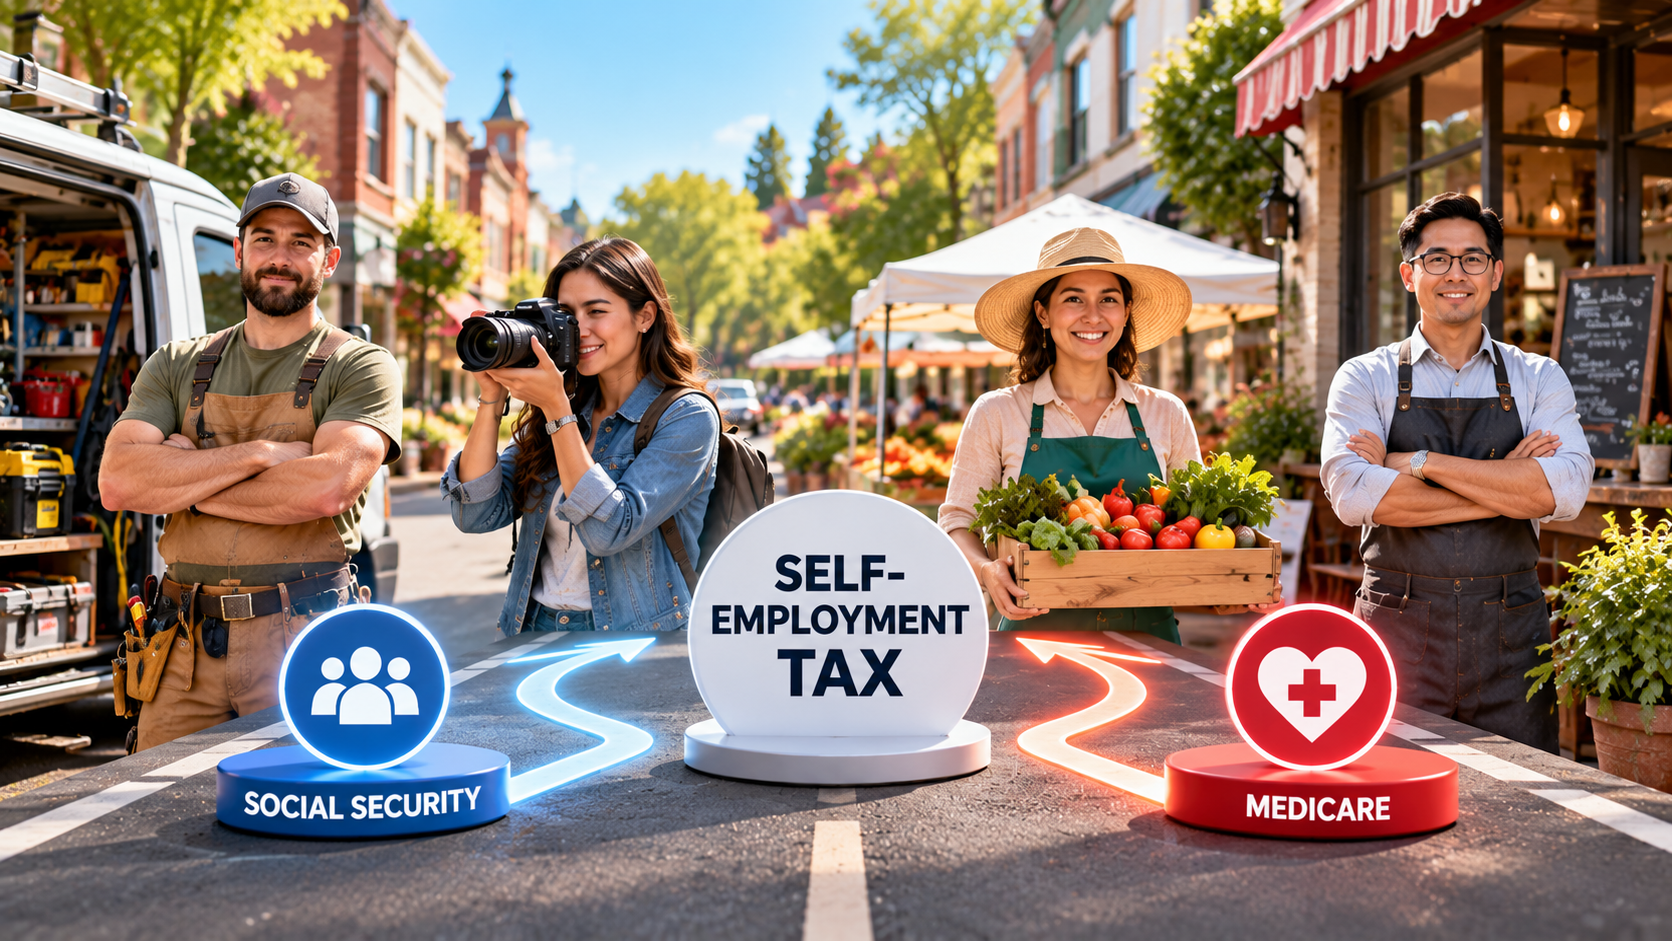
Working for yourself changes more than where your paycheck comes from. It also changes how Social Security and Medicare taxes are collected.
Employees generally split these taxes with their employers. If you’re self-employed, you generally account for both portions through self-employment tax.
That doesn’t mean you pay 15.3% of everything your business earns. Here’s how the calculation actually works.
Affiliate Disclosure: This article contains affiliate links. If you join Wealthy Affiliate through one of my links, I may earn a commission at no additional cost to you. I recommend only products and services I have personally used or genuinely believe will add value for my readers. All opinions expressed in this review are my own.
What Is Self-Employment Tax?
Self-employment tax is the federal Social Security and Medicare tax that generally applies to net earnings from self-employment.
For 2026, the combined rate remains 15.3%, consisting of:
- 12.4% for Social Security
- 2.9% for Medicare
Self-employment tax is separate from federal income tax so that a self-employed person may owe both.
Who Pays Self-Employment Tax?
You generally owe self-employment tax when your net earnings from self-employment from all businesses total $400 or more.
This commonly includes sole proprietors, independent contractors, freelancers, certain partners, and owners of single-member LLCs treated as disregarded entities for federal income-tax purposes.
Simply receiving a Form 1099 doesn’t automatically determine whether you’re self-employed; the underlying working relationship and nature of the activity matter.
Hobby income also shouldn’t automatically be treated as self-employment income. Whether an activity constitutes a trade or business can affect its tax treatment.
How Is Self-Employment Tax Calculated?
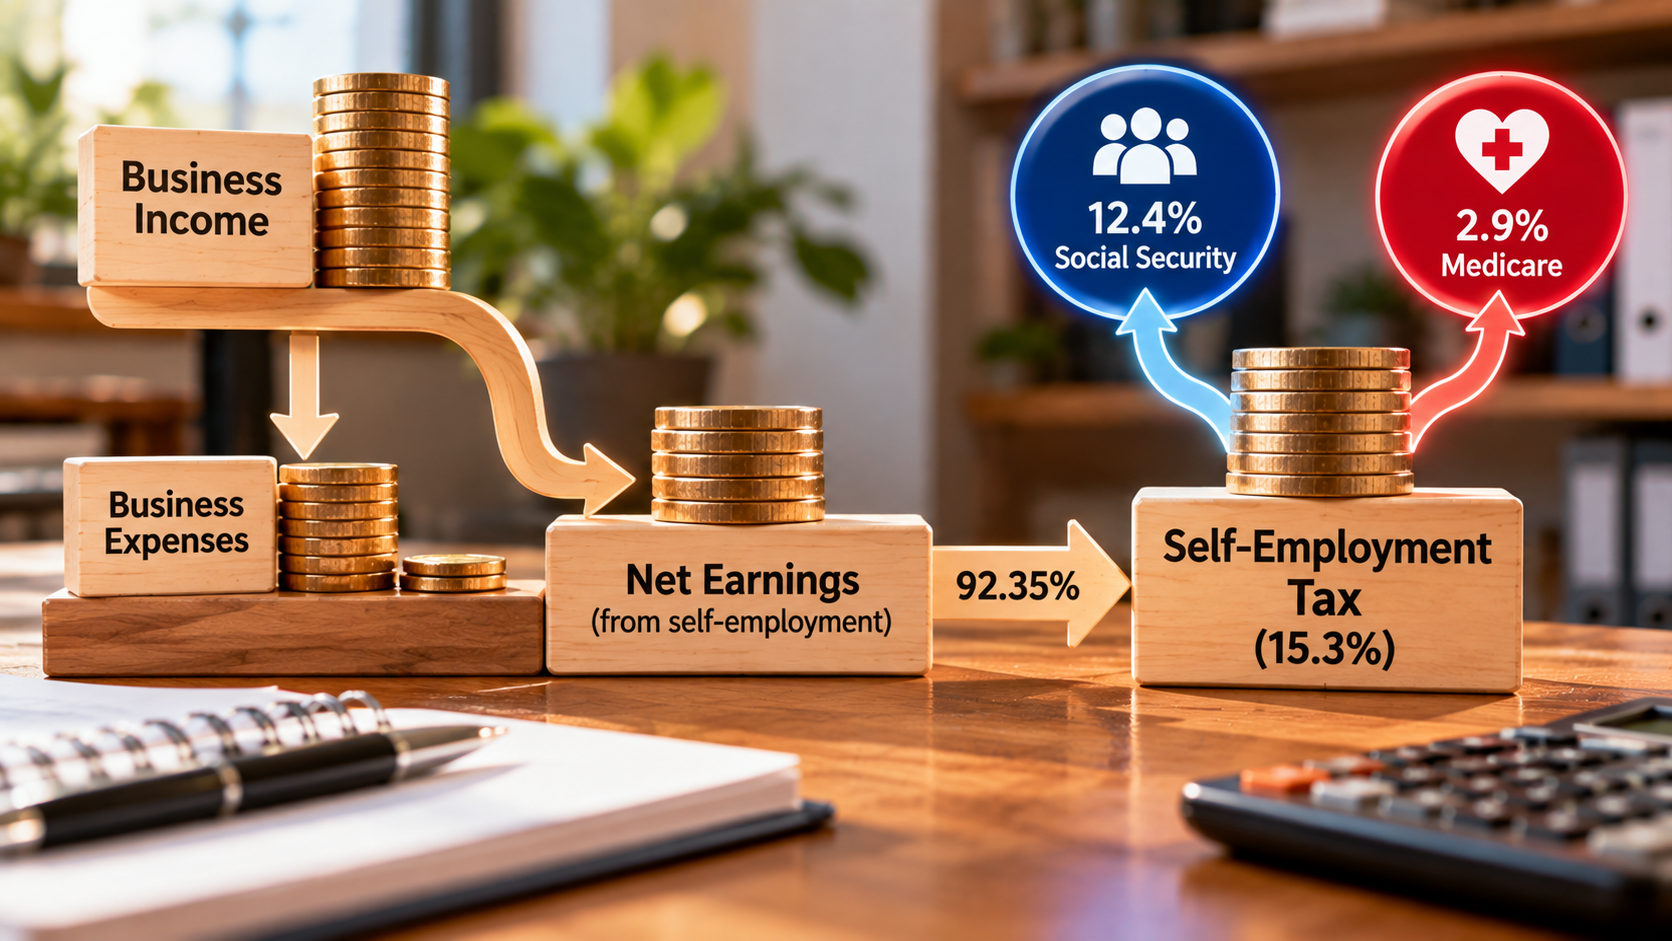
One of the biggest misconceptions is that you multiply business profit by 15.3%.
Generally, the calculation starts with 92.35% of your net earnings from self-employment.
Here’s a simplified example:
Business revenue: $60,000
Allowable business expenses: $20,000
Net business profit: $40,000
The amount generally used for the initial self-employment tax calculation would be:
$40,000 × 92.35% = $36,940
Assuming no other wages and that the amount remains below the Social Security wage base, applying 15.3% gives approximately:
$36,940 × 15.3% = $5,651.82
That’s separate from any federal income tax the taxpayer may owe.
Accurate self-employment tax starts with knowing what your business actually earned and spent. See how IntegriBooks can help keep your small-business books organized and tax-ready.
What Is the 2026 Social Security Wage Base?
The Social Security portion doesn’t apply without limit.
For 2026, the Social Security wage base is $184,500.
That means the 12.4% Social Security component applies only up to the applicable combined wage-base limit.
The 2.9% Medicare portion doesn’t have the same income cap.
Because the Social Security wage base changes periodically, future readers should use the limit applicable to the tax year they’re filing.
What If You Have a W-2 Job and a Side Business?
Having a regular job doesn’t eliminate self-employment tax on qualifying business income.
However, your W-2 Social Security wages matter.
Suppose you earn wages from an employer and also operate a profitable side business. Social Security tax already paid through your W-2 employment counts toward the annual Social Security wage base.
If your wages reach the annual limit, additional self-employment earnings generally aren’t subject to the 12.4% Social Security component.
The Medicare portion can still apply.
This is why someone with both W-2 wages and business income shouldn’t calculate the two sources independently without considering how they interact.
What Is Additional Medicare Tax?
Certain higher-income taxpayers may also owe a 0.9% Additional Medicare Tax.
The thresholds are based on filing status:
Married filing jointly: $250,000
Married filing separately: $125,000
All other taxpayers: $200,000
The calculation can involve a combination of Medicare wages, qualifying railroad retirement compensation, and self-employment income.
If you have both W-2 wages and self-employment income, you don’t compare only your business income to the threshold.
Additional Medicare Tax is calculated separately from the regular 2.9% Medicare component.
Schedule C vs. Schedule SE
These two tax forms perform different jobs.
Schedule C is generally where a sole proprietor reports business income and deductible business expenses to determine profit or loss.
Schedule SE is used to calculate self-employment tax based on qualifying net earnings.
In simplified terms:
Business income − allowable business expenses → Schedule C profit
Then:
Qualifying net earnings → Schedule SE → self-employment tax
Partners and certain other self-employed taxpayers can receive self-employment income through other forms instead of Schedule C.
Can You Deduct Half of Your Self-Employment Tax?
Generally, you can claim an income-tax deduction for the employer-equivalent portion of self-employment tax.
This is an adjustment when determining adjusted gross income.
Importantly, this deduction doesn’t mean the IRS refunds half your self-employment tax, and it doesn’t simply cut the self-employment-tax calculation in half.
It primarily affects your income-tax calculation.
What About Health Insurance and Retirement Contributions?
Eligible self-employed individuals may qualify for a separate deduction for certain self-employed health-insurance costs, subject to applicable requirements and limitations.
Self-employed business owners may also have retirement options such as SEP IRAs, SIMPLE IRAs, or qualified plans, including certain one-participant 401(k) arrangements.
These provisions can potentially reduce taxable income, but they don’t necessarily reduce net earnings subject to self-employment tax.
Treat each deduction according to its own rules rather than assuming every tax deduction reduces both income tax and self-employment tax.
Do Self-Employed People Have to Pay Quarterly Taxes?
Not automatically.
For 2026, individuals generally need estimated tax payments when both of these conditions apply:
- You expect to owe at least $1,000 after subtracting withholding and applicable credits; and
- Your expected withholding and credits will be less than the smaller of 90% of your 2026 tax or 100% of your 2025 tax, assuming the prior return covered 12 months.
For certain higher-income taxpayers, the prior-year safe-harbor percentage generally becomes 110% when prior-year adjusted gross income exceeds $150,000, or $75,000 if married filing separately.
Estimated payments can cover both income tax and self-employment tax.
If you also have a W-2 job, increasing withholding from your paycheck may sometimes help cover taxes generated by your side business.
Does Forming an LLC Eliminate Self-Employment Tax?
No.
An LLC is a state-law business structure, while its federal tax treatment depends on its tax classification.
For example, a single-member LLC treated as a disregarded entity generally reports business activity similarly to a sole proprietor, and qualifying net earnings can remain subject to self-employment tax.
A multi-member LLC taxed as a partnership follows different rules.
An eligible LLC may also elect corporate taxation, including potentially S corporation treatment. That changes how employment and self-employment taxes can apply, but an S election comes with additional payroll, reasonable-compensation, filing, and compliance requirements.
Don’t choose a business structure solely to avoid self-employment tax.
What Records Should Self-Employed Business Owners Keep?
Good bookkeeping helps establish both business income and legitimate deductible expenses.
Useful records can include invoices, receipts, bank and credit-card statements, mileage records, contracts, payment records, asset-purchase documents, and other records supporting business transactions.
There isn’t one universal retention period for every record. Keep records for as long as they’re needed to substantiate income, deductions, asset basis, or other information reported on tax returns.
Separating business and personal transactions can also make bookkeeping and tax preparation considerably easier.
Federal vs. State Taxes
The self-employment tax discussed here is a federal Social Security and Medicare tax.
State obligations are separate.
Depending on where you live or operate, you may also face state income taxes, estimated payments, sales or use taxes, franchise or business taxes, payroll obligations, or local taxes.
Don’t assume your federal self-employment-tax calculation determines what you owe your state.
Common Self-Employment Tax Mistakes
Common problems include calculating 15.3% directly from gross revenue, forgetting the 92.35% calculation, using an outdated Social Security wage base, ignoring W-2 wages when calculating the Social Security portion, confusing business deductions with deductions that only affect income tax, and assuming every self-employed person automatically needs quarterly payments.
Another frequent mistake is waiting until tax season to organize an entire year’s business activity.
Self-Employment Tax FAQs
Is self-employment tax the same as income tax?
No. Self-employment tax primarily funds Social Security and Medicare. Federal income tax is calculated separately.
Is all business revenue subject to self-employment tax?
Generally, no. For a typical sole proprietor, allowable business expenses are deducted in determining net profit, and Schedule SE generally applies the 92.35% calculation to qualifying net earnings.
Do I owe self-employment tax if I make less than $400?
Generally, self-employment tax applies when total net earnings from self-employment are $400 or more, although special rules exist for certain taxpayers.
Does an S corporation pay self-employment tax?
S corporation pass-through income generally isn’t self-employment income. However, shareholder-employees who perform services for the corporation are subject to reasonable-compensation rules, and their wages are generally subject to employment taxes.
Keep Your Business Records Tax-Ready
Self-employment tax becomes much easier to understand when you record your revenue, expenses, and business profit accurately throughout the year.
Good bookkeeping won’t eliminate taxes you legitimately owe. Still, it can help you calculate them correctly, identify allowable business expenses, prepare for estimated payments, and avoid reconstructing months of transactions at tax time.
Want cleaner records before your next tax deadline? Visit IntegriBooks to learn how professional bookkeeping support can help keep your business finances organized throughout the year.