Running a business costs money. Fortunately, many legitimate business expenses can reduce the income that’s subject to tax.
But a tax deduction isn’t simply something you bought while running a business. The expense generally must satisfy federal tax rules; some costs are fully deductible, some are partially deductible, and others may need to be depreciated or treated differently.
Here’s what small business owners should know before calling something a “write-off.”
Affiliate Disclosure: This article contains affiliate links. If you join Wealthy Affiliate through one of my links, I may earn a commission at no additional cost to you. I recommend only products and services I have personally used or genuinely believe will add value for my readers. All opinions expressed in this review are my own.
What Is a Small Business Tax Deduction?
A business tax deduction generally reduces taxable business income.
For example, suppose a business has:
$100,000 in revenue
$30,000 in allowable business expenses
$70,000 in net business income
That doesn’t necessarily mean the owner pays tax on exactly $70,000. The final tax calculation depends on the business structure, other income, deductions, credits, and other tax rules.
Still, properly identifying business expenses is essential to accurately calculating business profit.
What Does “Ordinary and Necessary” Mean?
A business expense generally must be ordinary and necessary to be deductible.
An ordinary expense is common and accepted in your trade or business.
A necessary expense is helpful and appropriate for the business. It doesn’t have to be essential.
For example, tools a handyman buys or bookkeeping software a small retailer uses could meet that standard.
Personal expenses generally aren’t deductible just because you’re a business owner.
What Business Expenses Can You Write Off?
Depending on the business and circumstances, common deductible expenses can include:
- Advertising and marketing
- Office or commercial rent
- Business insurance
- Office supplies
- Software and subscriptions
- Legal and accounting services
- Employee compensation
- Qualifying payments to independent contractors
- Business-related education
- Certain interest and taxes
- Repairs and maintenance
- Qualifying travel expenses
- Business use of a vehicle
- Qualifying home-office expenses
The tax treatment isn’t necessarily identical for every expense. Some purchases may need to be capitalized or depreciated rather than immediately deducted.
Finding deductions is much easier when your business transactions are already properly categorized. See how IntegriBooks can help keep your books organized and tax-ready.
Can You Deduct Business Meals?
Qualifying business meals are generally 50% deductible under current federal rules.
A deductible business meal generally needs to be ordinary and necessary, not lavish under the circumstances, and involve the taxpayer or an employee being present.
When a meal is connected with an entertainment event, the food and beverages generally must be purchased separately or stated separately from the entertainment cost to qualify.
Entertainment expenses themselves are generally not deductible merely because business was discussed.
Can You Deduct a Home Office?
Possibly.
The home-office deduction has specific requirements. For many business owners, the space must be used regularly and exclusively for business and meet another qualifying-use requirement, such as being the principal place of business.
A spare bedroom used exclusively as an office may qualify. A kitchen table the family regularly uses generally won’t satisfy the exclusive-use requirement.
Eligible taxpayers may use either the regular method, based on qualifying actual expenses, or the simplified method.
Special rules and exceptions apply to certain situations, including daycare facilities and storage of inventory or product samples.
Can You Deduct Your Vehicle?
You may deduct business use of a vehicle, but personal use and normal commuting generally aren’t business expenses.
Eligible taxpayers may use an applicable standard mileage method or calculate qualifying actual vehicle expenses, subject to the rules governing each method.
For 2026, the IRS business standard mileage rate changed during the year:
January 1–June 30, 2026: 72.5 cents per business mile
July 1–December 31, 2026: 76 cents per business mile
Because mileage rates can change, future readers should always check the rate for the applicable tax year.
Keep a reliable mileage record showing business miles, dates, destinations, and business purpose.
Are Business Gifts Deductible?
Business gifts have a surprisingly low federal deduction limit.
Generally, you can deduct no more than $25 of business gifts given directly or indirectly to any one person during the tax year.
Certain incidental costs and qualifying low-cost promotional items are treated differently.
Don’t assume that spending $100 on a client gift automatically produces a $100 deduction.
Can You Deduct Startup Costs?
Startup expenses are treated differently from ordinary expenses incurred by an operating business.
Under current federal rules, an eligible business may generally deduct up to $5,000 of qualifying startup costs and up to $5,000 of qualifying organizational costs, subject to applicable limitations and phaseouts when total costs exceed specified thresholds.
You generally amortize remaining qualifying costs over the required period.
Startup costs can include certain expenses incurred while investigating or creating a business before active operations begin.
Because timing and classification matter, keep pre-opening expenses separate from normal operating expenses.
Can You Immediately Deduct Equipment?
Sometimes—but don’t assume every piece of equipment is an immediate write-off.
Computers, machinery, furniture, vehicles, and other longer-lived business property may be subject to depreciation rules.
Depending on the property and circumstances, businesses may have options such as Section 179 expensing, bonus depreciation, or other available elections.
Dollar limits and depreciation rules can change, so evaluate major purchases using the rules applicable to the year the property is placed in service.
What Expenses Generally Aren’t Deductible?
Common examples of expenses that generally aren’t deductible as ordinary business expenses include personal expenses, normal commuting, political contributions, many lobbying expenses, government fines and penalties, and certain club dues.
Mixed personal-and-business expenses require particular care. If a phone, vehicle, internet connection, or similar item is used for both purposes, only the qualifying business portion may be deductible.
Labeling a personal purchase as a business expense doesn’t make it deductible.
Tax Deduction vs. Tax Credit: What’s the Difference?
These terms aren’t interchangeable.
A tax deduction generally reduces taxable income.
A tax credit generally reduces tax liability, subject to the particular credit’s rules.
Suppose you receive a $2,000 deduction. That doesn’t normally mean your tax bill automatically falls by $2,000.
A $2,000 tax credit may reduce tax liability by as much as $2,000, although whether a credit is refundable, nonrefundable, limited, phased out, or otherwise restricted depends on the specific credit.
That’s why comparing deductions and credits by dollar amount alone can be misleading.
What Records Should You Keep for Business Deductions?
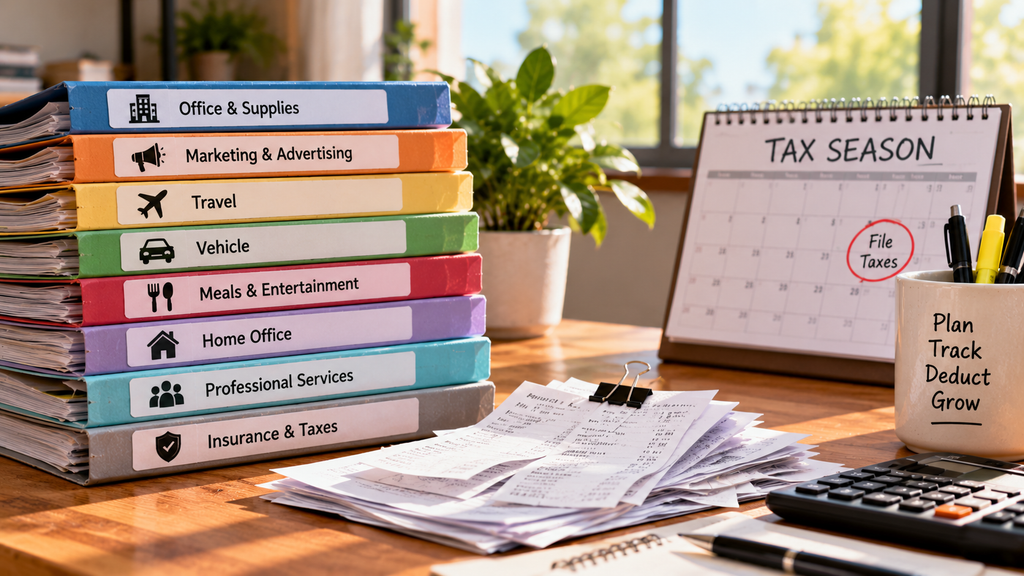
Good records should establish the amount, date, and business purpose of expenses and provide whatever additional substantiation the particular deduction requires.
Useful records can include receipts, invoices, canceled checks or payment records, bank and credit-card statements, mileage records, travel documentation, contracts, and records relating to business assets.
The often-mentioned $75 receipt rule isn’t a universal rule saying expenses below $75 require no documentation. Special substantiation rules apply to categories such as travel, gifts, and vehicles, and lodging generally has its own documentation requirements.
There also isn’t one universal rule requiring every business document to be discarded after three years.
Keep records for as long as they may be needed to support a tax return or establish matters such as asset basis. Some records, including certain employment-tax and property records, may need to be retained longer.
Federal Deductions vs. State Tax Rules
Federal deductibility doesn’t necessarily determine how your state will treat an expense.
States can have different rules involving income taxes, depreciation, business credits, pass-through entities, sales taxes, and other items.
Businesses operating in multiple states can face additional complexity.
Treat federal and state tax compliance as related—but separate—questions.
Common Small Business Deduction Mistakes
Some of the most avoidable problems happen when business owners mix personal and business spending, estimate expenses without adequate records, deduct 100% of mixed-use costs, overlook capitalization rules, or assume something is deductible simply because another business owner deducted it.
A separate business bank account and credit card can make recordkeeping easier, but the account used to pay an expense doesn’t determine whether the expense is deductible.
The underlying expense still has to qualify.
Small Business Tax Deduction FAQs
Can I deduct every expense related to my business?
No. The expense must satisfy the applicable tax rules, and some costs may be limited, capitalized, depreciated, amortized, or nondeductible.
Are client meals always 50% deductible?
No. The meal must first satisfy the applicable business-meal requirements. When it qualifies, the deduction is generally limited to 50%.
Can I deduct equipment in the year I buy it?
Potentially. The treatment depends on the property, when it’s placed in service, business use, and available depreciation or expensing provisions.
Do I need a receipt for every deduction?
You need records sufficient to substantiate your deductions under the applicable rules. Don’t treat $75 as a blanket threshold below which recordkeeping doesn’t matter.
Better Records Make Better Tax Deductions
The goal isn’t to find the largest possible list of “write-offs.” It’s to identify legitimate business expenses, classify them correctly, and maintain records that support them.
Good bookkeeping makes that much easier. Instead of reconstructing a year’s worth of spending at tax time, you can see what the business spent, why it spent it, and how it categorized it.
Want cleaner records before tax season? Visit IntegriBooks to learn how organized bookkeeping can help your business track expenses and stay better prepared throughout the year.