Running a business changes how you pay taxes.
Employees typically have federal income tax withheld from their paychecks. But if you earn money from self-employment, freelancing, contract work, investments, or other income and don’t have enough withheld, you may need to make estimated tax payments during the year.
For small business owners, understanding estimated taxes can help prevent an unexpectedly large tax bill and reduce the risk of an underpayment penalty.
Here’s how the system works.
Affiliate Disclosure: This article contains affiliate links. If you join Wealthy Affiliate through one of my links, I may earn a commission at no additional cost to you. I recommend only products and services I have personally used or genuinely believe will add value for my readers. All opinions expressed in this review are my own.
What Are Estimated Taxes?
Estimated taxes are payments made during the year toward taxes not covered through withholding.
For many self-employed business owners, those payments may cover both:
- Federal income tax
- Self-employment tax
They may also need to account for other taxes depending on their circumstances.
The federal tax system generally operates on a pay-as-you-go basis. That means you are expected to pay taxes as you earn income rather than waiting until you file your annual tax return.
Who May Need to Pay Estimated Taxes?
Estimated payments commonly affect:
- Sole proprietors
- Independent contractors and freelancers
- Partners
- Certain LLC owners
- S corporation shareholders
- People with significant side-business income
- People with other income that isn’t sufficiently covered by withholding
Corporations have separate estimated-tax rules, so don’t assume the individual rules discussed here apply to every business entity.
Having a business doesn’t automatically mean you must make estimated payments. The amount of tax you expect to owe and the withholding and credits available to you matter.
The $1,000 Estimated-Tax Rule
For individuals, the IRS generally says estimated tax payments are required if both of these conditions apply:
- You expect to owe at least $1,000 in tax for the year after subtracting withholding and refundable credits; and
- Your withholding and refundable credits are expected to be less than the smaller of the applicable safe-harbor amounts discussed below.
That makes the $1,000 figure important—but it isn’t the entire test.
Someone with wages from a regular job, for example, might have enough withholding from those wages to cover the tax generated by a side business.
How the Estimated-Tax Safe Harbor Works
The safe-harbor rules can help taxpayers determine how much generally needs to be prepaid to avoid an underpayment penalty.
For most individuals, the required annual payment is generally the smaller of:
90% of the tax expected for the current year, or
100% of the tax shown on the previous year’s return, provided that prior return covered a full 12-month year.
For certain higher-income taxpayers, the prior-year amount generally increases from 100% to 110%. For 2026, that generally applies when 2025 adjusted gross income exceeded $150,000, or $75,000 for married taxpayers filing separately.
Special rules apply in some situations, including farming and fishing.
Also remember that meeting a safe harbor doesn’t necessarily mean you have paid your entire tax bill. You could avoid an estimated-tax penalty and still owe additional tax when you file your return.
Accurate estimated taxes start with accurate financial records. See how IntegriBooks can help keep your business books organized and tax-ready.
What Is Self-Employment Tax?
For many sole proprietors, freelancers, and independent contractors, estimated taxes need to account for self-employment tax as well as income tax.
The self-employment tax rate is generally 15.3%, consisting of:
12.4% for Social Security
2.9% for Medicare
However, saying business owners pay 15.3% of all business profit is inaccurate.
Under the regular calculation, 92.35% of net self-employment earnings is generally used when calculating self-employment tax. The Social Security portion is also subject to an annual wage base, while Medicare rules differ.
For 2026, the Social Security wage base is $184,500. Because that amount can change annually, business owners should verify the current year’s figure rather than relying on an older article.
Additional Medicare Tax may also apply in certain higher-income situations.
How Do You Calculate Estimated Taxes?
Individual taxpayers can use Form 1040-ES and the IRS estimated-tax worksheets to help calculate required payments.
The process generally involves estimating:
Expected income
Include relevant business and other taxable income.
Business expenses
Estimate ordinary and necessary deductible business expenses.
Adjusted gross income and deductions
These affect estimated taxable income.
Income tax
Estimate federal income tax based on the year’s applicable rules.
Self-employment tax
Include it when applicable.
Credits and withholding
Factor in expected tax credits and federal withholding.
Your previous year’s return can provide a useful starting point, but don’t assume this year’s results will be identical.
If revenue, expenses, employment, investments, or other circumstances change substantially, revisit the calculation.
Are Estimated Taxes Always Four Equal Payments?
Not necessarily.
Many taxpayers calculate a required annual amount and pay it in four installments. But income isn’t always earned evenly throughout the year.
A seasonal business might earn most of its profit during a few months. Another business might receive a large contract late in the year.
The IRS provides an annualized income installment method that may help taxpayers whose income varies significantly determine required installments based more closely on when they earned the income.
This method is more complicated, so businesses with highly seasonal or irregular income may benefit from professional tax guidance.
When Are Federal Estimated Taxes Due?
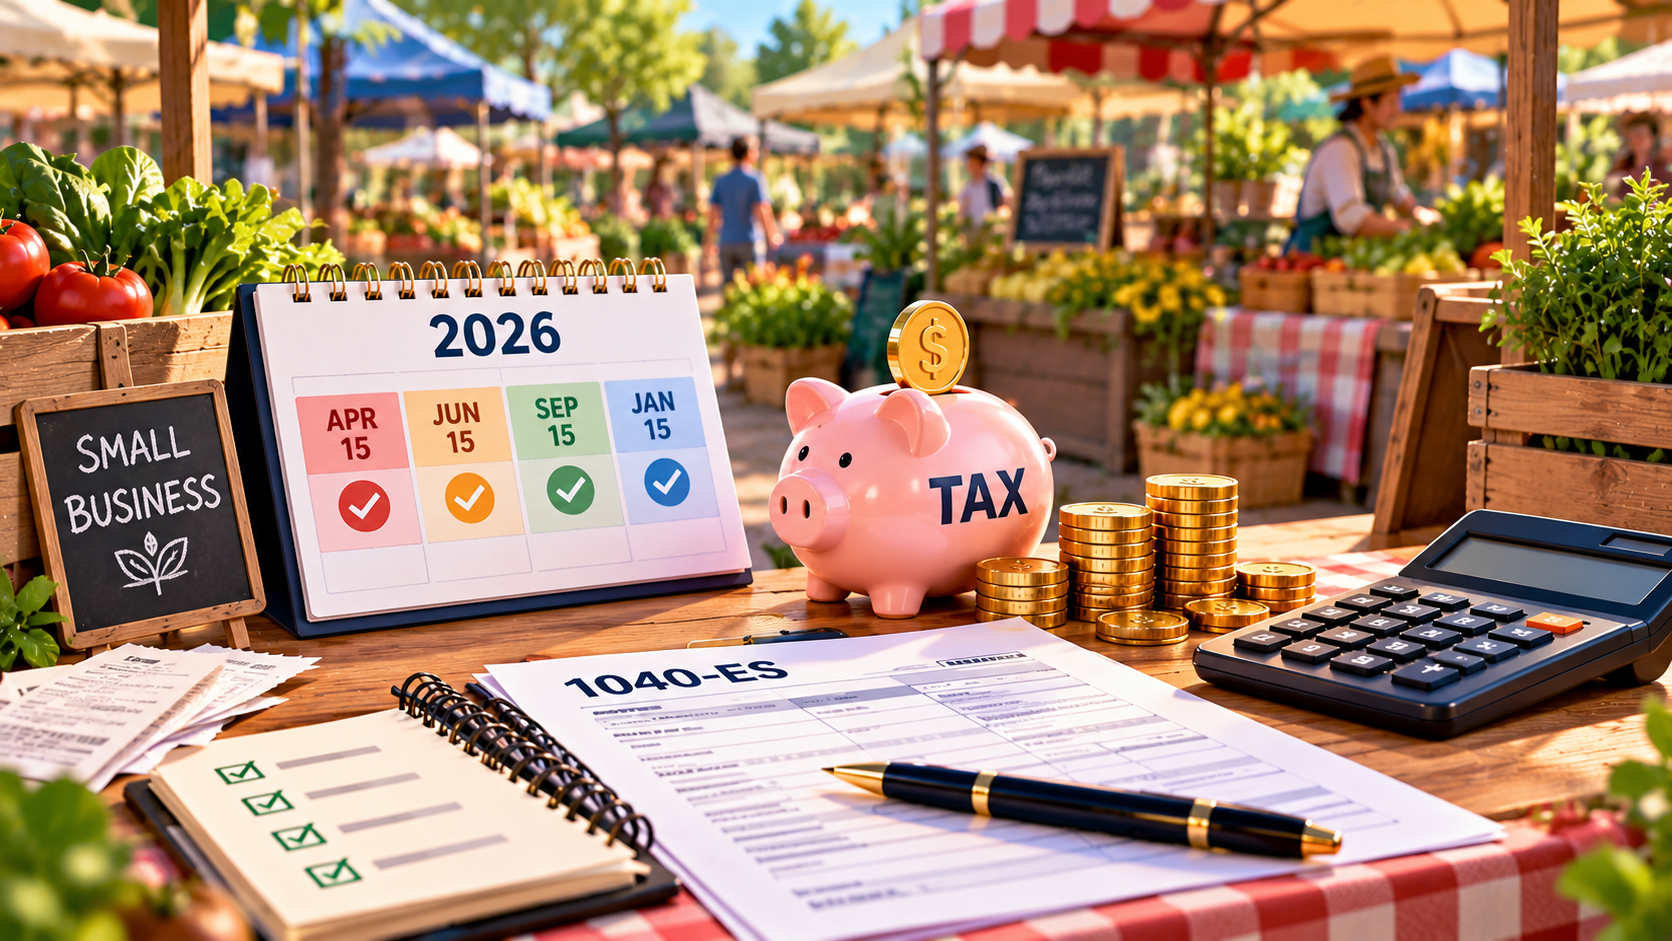
For calendar-year individual taxpayers, the general payment schedule is:
| Income period | General payment deadline |
|---|---|
| January 1–March 31 | April 15 |
| April 1–May 31 | June 15 |
| June 1–August 31 | September 15 |
| September 1–December 31 | January 15 of the following year |
If a deadline falls on a weekend or legal holiday, the due date generally moves to the next applicable business day.
For 2026 estimated taxes, those installment dates are April 15, 2026; June 15, 2026; September 15, 2026; and January 15, 2027.
Because dates can vary with weekends, holidays, fiscal years, and special circumstances, verify the applicable deadlines each year.
What If Your Income Changes During the Year?
You don’t have to unquestioningly continue using an estimate that no longer reflects your business.
Suppose sales increase dramatically halfway through the year. Your expected tax may increase as well.
On the other hand, a significant decline in income or increase in deductible expenses could reduce the amount ultimately owed.
Review your year-to-date profit and tax position periodically and update estimates when circumstances materially change.
Good bookkeeping matters here because estimates based on incomplete records can create a false sense of accuracy.
What About State Estimated Taxes?
Federal estimated taxes are only one part of the picture.
Many states impose their own income taxes and estimated-payment requirements, but thresholds, deadlines, calculations, safe harbors, forms, and payment procedures can differ from federal rules.
Some states don’t impose an individual income tax, while others have their own estimated-tax systems.
If your business operates in more than one state—or you live in one state while earning business income in another—the situation can become more complicated.
Always check the rules for the state or states that apply to your specific situation.
What Happens If You Don’t Pay Enough?
An underpayment of estimated tax penalty may apply when required payments aren’t sufficient or aren’t made on time.
Importantly, simply paying the full balance when you file your annual return doesn’t necessarily eliminate an earlier underpayment.
The penalty calculation considers when payments were required and when they were actually made.
Exceptions and situations may reduce or waive a penalty, but they depend on specific circumstances.
How to Budget for Estimated Taxes
The IRS doesn’t prescribe one universal percentage that every small business should save for taxes.
That’s because the appropriate amount depends on profit, filing status, other household income, deductions, credits, withholding, state taxes, and other factors.
A better approach is to:
- Maintain current bookkeeping.
- Review profit regularly.
- Keep tax money separate from normal operating funds when practical.
- Recalculate estimates after significant financial changes.
- Keep records of payments.
- Work with a qualified tax professional when your situation warrants it.
Avoid relying on a generic rule such as “save 25%” or “save 30%” without considering your actual tax situation.
Frequently Asked Questions
Can I make estimated tax payments more frequently?
You can make payments more frequently than four times per year. However, what ultimately matters for underpayment purposes is whether you’ve paid enough tax by the applicable installment deadlines.
What if I also have a regular job?
Business owners with wage income may be able to increase withholding from their paycheck instead of—or in addition to—making separate estimated payments. The appropriate approach depends on the overall tax situation.
Do I automatically need estimated taxes if I’m self-employed?
No. Whether estimated payments are required depends on expected tax liability, withholding, credits, and other applicable rules.
Can accounting software calculate my estimated taxes?
Software can help organize financial information, and some products may provide tax estimates, but those calculations depend on the information and assumptions you enter. Don’t treat software as a substitute for verifying your tax situation.
Stay Ahead of Estimated Taxes
Estimated taxes are much easier to manage when you treat them as part of normal business financial planning rather than an unexpected bill every few months.
Keep your books current, understand the $1,000 threshold and safe-harbor rules, review profit throughout the year, and adjust when your business changes.
Most importantly, remember that estimated taxes are estimates. Good records give you a much stronger foundation for making them.
Better tax planning begins with knowing what your business actually earned and spent. Visit IntegriBooks to learn how organized bookkeeping can help you stay prepared year-round.