Running a business as a sole proprietor can be relatively straightforward, but the tax side can feel confusing when you’re just getting started.
Unlike a corporation, a sole proprietorship generally doesn’t file a separate federal income tax return. Instead, the business reports its income and expenses on the owner’s individual federal tax return.
That means understanding a few key concepts—Schedule C, self-employment tax, estimated taxes, deductions, and recordkeeping—can make tax season much easier to manage.
Affiliate Disclosure: This article contains affiliate links. If you join Wealthy Affiliate through one of my links, I may earn a commission at no additional cost to you. I recommend only products and services I have personally used or genuinely believe will add value for my readers. All opinions expressed in this review are my own.
How Are Sole Proprietors Taxed?
For federal income tax purposes, a sole proprietorship isn’t a separate entity from its owner.
If you operate a qualifying trade or business as a sole proprietor, you generally report its income and expenses on Schedule C, Profit or Loss From Business, which is filed with your Form 1040.
Your Schedule C calculates the business’s net profit or loss.
A simplified example:
Business revenue: $60,000
Allowable business expenses: $15,000
Net business profit: $45,000
That $45,000 isn’t necessarily your final taxable income. Other parts of your tax return, including adjustments, deductions, other income, credits, and your filing status, also affect your overall federal income-tax calculation.
What Is Schedule C?
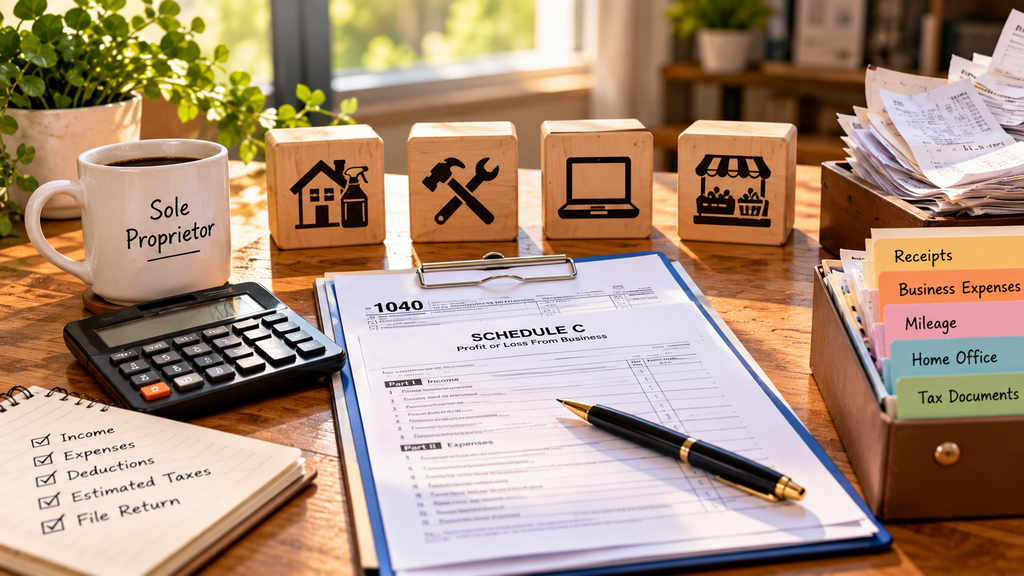
Schedule C is one of the main federal tax forms sole proprietors use.
It reports information such as:
- Gross receipts or sales
- Returns and allowances, when applicable
- Cost of goods sold, when applicable
- Ordinary and necessary business expenses
- Vehicle information when required
- Other qualifying business expenses
The result is generally your net business profit or loss.
One important distinction is that revenue isn’t the same as profit.
Revenue is generally the money your business earns before expenses. Net profit is what’s left after subtracting allowable business expenses.
Keeping those numbers separate is essential for understanding how your business is actually performing.
What Is Self-Employment Tax?
Sole proprietors may owe self-employment tax in addition to federal income tax.
Self-employment tax primarily funds Social Security and Medicare.
The standard rate is 15.3%, consisting of:
12.4% Social Security tax
2.9% Medicare tax
However, multiplying your entire business profit by 15.3% would be misleading.
Generally, 92.35% of net earnings from self-employment is used when calculating self-employment tax. The Social Security portion is also subject to an annual wage base, which can change each year.
Sole proprietors generally use Schedule SE to calculate self-employment tax when net earnings from self-employment from all businesses are $400 or more.
Certain higher-income taxpayers may also be subject to Additional Medicare Tax.
You may generally deduct the employer-equivalent portion of your self-employment tax as an adjustment when calculating adjusted gross income. That deduction reduces income for income-tax purposes; it doesn’t simply erase half of the self-employment tax itself.
Accurate tax planning starts with knowing what your business actually earned and spent. See how IntegriBooks can help keep your small-business books organized and tax-ready.
Do Sole Proprietors Pay Quarterly Estimated Taxes?
They may.
Because sole proprietors don’t typically have taxes withheld from their business income, estimated tax payments are often necessary.
But the commonly mentioned $1,000 threshold isn’t the entire test.
For individuals, estimated tax payments are generally required when both of these conditions apply:
- You expect to owe at least $1,000 in tax for the year after subtracting withholding and refundable credits; and
- Your expected withholding and refundable credits will be less than the smaller of:
- 90% of the tax expected for the current year, or
- 100% of the tax shown on the previous year’s return, assuming that return covered 12 months.
For certain higher-income taxpayers, the prior-year percentage generally increases to 110%. For 2026 estimated taxes, that generally applies when 2025 adjusted gross income exceeded $150,000, or $75,000 for married taxpayers filing separately.
Special rules apply in certain circumstances, including farming and fishing.
Estimated payments for calendar-year individuals are generally due in April, June, September, and January of the following year. Please check the actual dates each year, as weekends, holidays, and individual circumstances can affect deadlines.
If your income is uneven or seasonal, the annualized income installment method may sometimes produce a different required-payment pattern than simply dividing an annual estimate into four equal amounts.
What Business Expenses Can a Sole Proprietor Deduct?
A deductible business expense generally must be ordinary and necessary for the trade or business.
“Ordinary” generally means common and accepted in the business. “Necessary” means helpful and appropriate—it doesn’t have to be absolutely indispensable.
Depending on the business and circumstances, potentially deductible expenses can include:
- Advertising and marketing
- Office supplies
- Business insurance
- Legal and professional services
- Business software and subscriptions
- Certain vehicle expenses
- Qualifying business travel
- Qualifying business meals, generally subject to applicable limitations
- Business-related phone and internet costs
- Certain home-office expenses
- Depreciation or other allowable treatment of business property
Not every purchase is immediately deductible.
Equipment, furniture, vehicles, software, improvements, and other assets can be subject to capitalization, depreciation, Section 179, safe-harbor elections, or other rules.
What About the Home-Office Deduction?
A home office doesn’t automatically qualify for a deduction just because you occasionally work from home.
Among other requirements, an area generally needs to be used regularly and exclusively for business, although special rules and exceptions apply in certain situations.
Both an actual-expense method and a simplified method may be available to qualifying taxpayers.
What Records Should Sole Proprietors Keep?
Good records should clearly show your business’s income and expenses and support the amounts reported on your tax return.
Depending on the business, useful records may include:
- Sales records and invoices
- Receipts and paid bills
- Bank and credit-card statements
- Deposit records
- Mileage and vehicle records
- Asset purchase information
- Payroll records if you have employees
- Documents supporting deductions and credits
A separate business bank account isn’t generally required for federal tax purposes for a sole proprietorship, but separating business and personal transactions can make bookkeeping and tax preparation much easier.
Personal expenses generally aren’t deductible merely because they’re paid from a business account.
How Long Should You Keep Business Records?
There isn’t one universal “keep everything for three years” rule.
The IRS says records should generally be kept as long as they may be needed to prove income, deductions, or other items on a tax return.
Different documents can have different retention periods. For example, employment-tax records generally need to be retained for at least four years.
Records concerning assets may need to be kept longer because they’re relevant for establishing basis, depreciation, and a later sale or disposition.
Instead of automatically deleting everything after three years, use a retention policy appropriate for the particular records involved.
What About State and Local Taxes?
Federal taxes are only part of a sole proprietor’s responsibilities.
Depending on where you operate and what you sell, state or local obligations can potentially include:
- State income tax
- Estimated state tax payments
- Sales and use taxes
- Local business taxes
- Payroll taxes
- Business licenses and permits
- Industry-specific taxes or fees
Rules vary considerably by location, so federal filing requirements shouldn’t replace checking applicable state and local requirements.
What If Your Sole Proprietorship Has a Loss?
If allowable business expenses exceed business income, Schedule C may report a net loss.
However, a business loss doesn’t automatically mean you can use the entire amount to reduce other taxable income.
Several tax provisions can potentially limit losses, and an activity must genuinely qualify as a trade or business rather than being treated as a not-for-profit activity.
Significant or recurring losses are a good reason to seek individualized tax guidance.
Sole Proprietor Tax FAQs
Do I need a business license to file Schedule C?
A business license and federal tax reporting are separate issues. Licensing requirements depend on your location and business activity.
Can I prepare my own sole proprietor taxes?
Yes. Some sole proprietors prepare their own returns, while others use tax software or a tax professional. Complexity increases with employees, inventory, significant assets, multiple businesses, complicated deductions, or multi-state activity.
Do I need Schedule SE every year?
Generally, Schedule SE is used when your total net earnings from self-employment meet the applicable threshold—currently generally $400 or more.
Can I form an LLC later?
Yes. A sole proprietor may decide to form an LLC as the business changes. But an LLC is a state-law structure, and forming one doesn’t automatically change federal income-tax treatment. Consider the legal, tax, administrative, and state consequences before changing structures.
Keep Your Books Ready for Tax Time
Sole proprietor taxes are much easier to manage when you keep books throughout the year instead of reconstructing them at tax time.
Track revenue, categorize expenses correctly, reconcile accounts, retain supporting records, and review your profit regularly. Those habits make it easier to estimate taxes, prepare Schedule C, identify legitimate deductions, and understand how the business is actually performing.
Want cleaner financial records before your next tax deadline? Visit IntegriBooks to learn how professional bookkeeping support can help keep your business finances organized throughout the year.