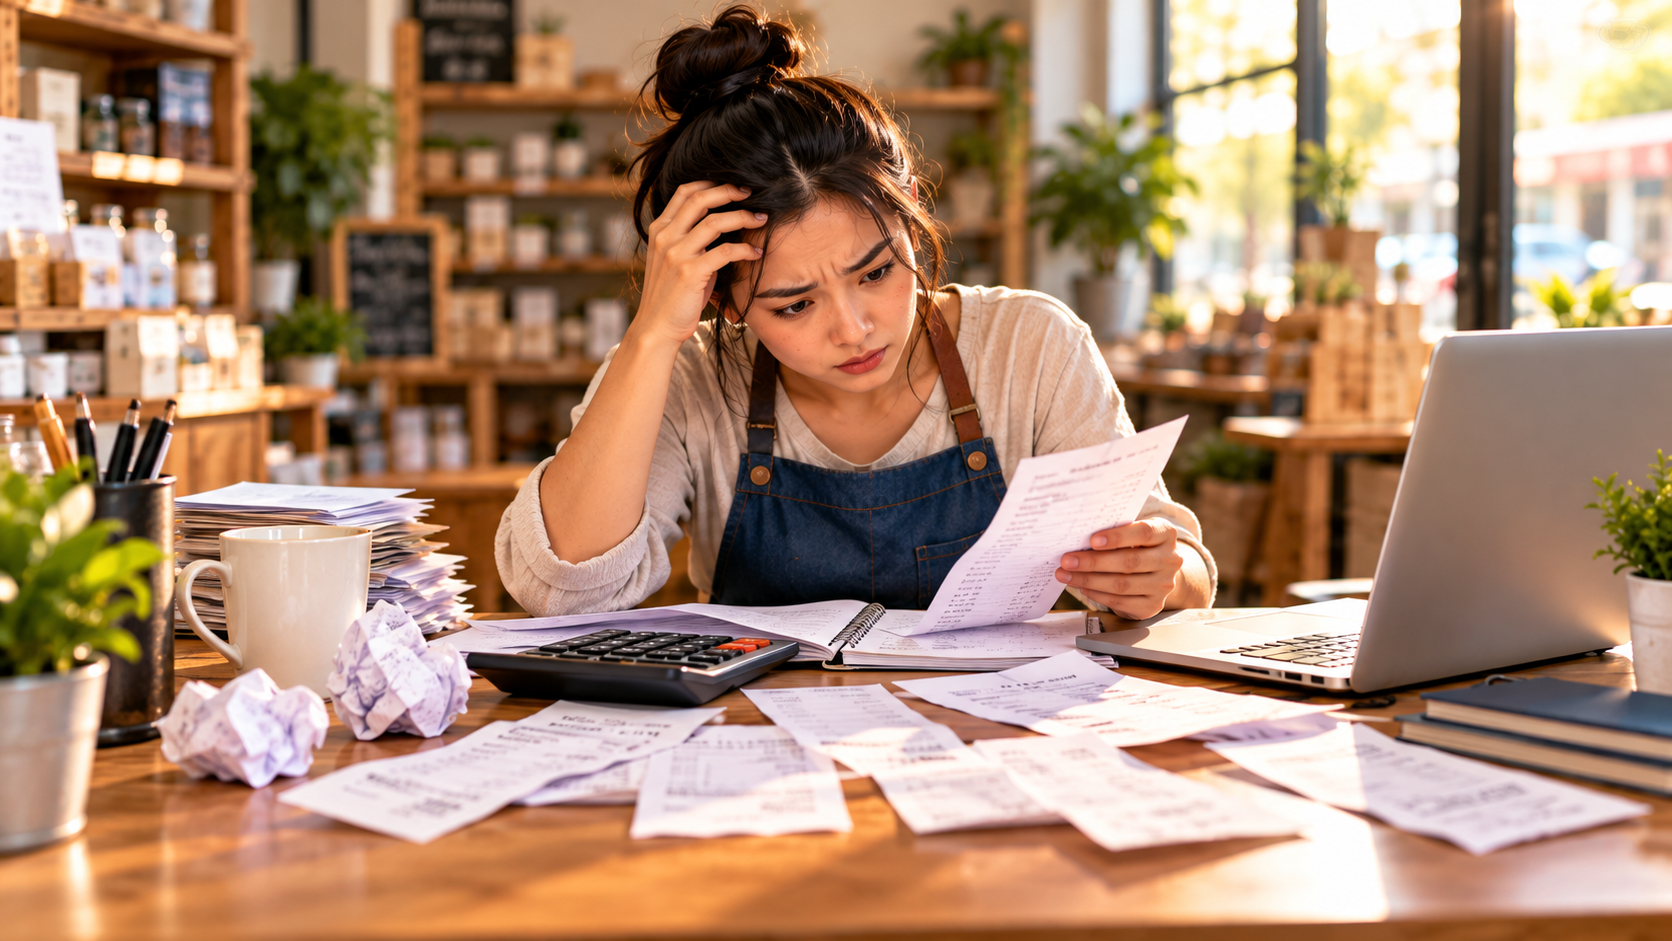
Bookkeeping mistakes don’t always announce themselves.
Sometimes they start with a missing receipt, a duplicate expense, or an invoice nobody followed up on. Everything might look fine until a supplier payment is due, your bank balance doesn’t match your records, or tax season arrives.
For small business owners, inaccurate bookkeeping can lead to cash flow problems, misleading financial reports, unnecessary expenses, and costly corrections.
Fortunately, a consistent process can prevent most common bookkeeping errors.
Here are 10 mistakes worth watching for, how they affect your business, and what you can do to fix them.
Affiliate Disclosure: This article contains affiliate links. If you join Wealthy Affiliate through one of my links, I may earn a commission at no additional cost to you. I recommend only products and services I have personally used or genuinely believe will add value for my readers. All opinions expressed in this review are my own.
1. Mixing Personal and Business Expenses
Using one bank account for everything might seem convenient, especially when you’re starting.
But mixing personal and business transactions makes it harder to identify deductible expenses, track profitability, and prepare accurate financial statements.
How to fix it: Use a dedicated business bank account and payment method. Record owner contributions, draws, and distributions correctly based on your business structure.
Federal tax law doesn’t automatically require a separate account for every sole proprietor, but it’s a useful bookkeeping practice.
2. Skipping Bank Reconciliation
Your bookkeeping software shows $8,000. Your bank statement says $6,500.
Where did the difference come from?
It could be an outstanding payment, missing transaction, duplicate entry, bank fee, or timing difference.
Without reconciliation, you might make spending decisions using inaccurate information.
How to fix it: Reconcile business bank and credit card accounts at least monthly. Compare transactions with statements and investigate discrepancies rather than entering unexplained adjustments to make balances match.
Bank feeds help import transactions, but they don’t replace reconciliation.
3. Confusing Profit With Available Cash
This is one of the most serious small business bookkeeping mistakes that affect cash flow.
Imagine your consulting business invoices a client for $5,000.
Under accrual accounting, the revenue may be recognized before payment arrives. Under cash accounting, income is generally recognized when received.
Either way, an unpaid invoice doesn’t provide cash to pay tomorrow’s bills.
How to fix it: Review your profit and loss statement alongside your bank balances, unpaid invoices, upcoming expenses, and cash flow forecast.
A profitable business can still run out of cash.
4. Categorizing Transactions Incorrectly
Not every deposit is revenue, and not every payment is an expense.
For example:
- Loan proceeds generally create a liability, not sales revenue.
- Loan principal payments generally reduce a liability rather than create an operating expense.
- Equipment purchases may require capitalization or another applicable tax treatment.
- Owner withdrawals generally aren’t ordinary business expenses.
Incorrect classifications can distort profit, liabilities, and tax-related records.
How to fix it: Maintain a clear chart of accounts and review unfamiliar transactions before categorizing them.
When necessary, have a qualified professional determine the proper accounting and tax treatment.
5. Recording Duplicate or Missing Transactions
Bookkeeping automation can save time, but it can also create problems when transactions are imported incorrectly.
For example, you might manually record a customer payment and then add the bank deposit as new income instead of matching the transactions.
That could overstate revenue.
How to fix it: Review imported transactions, match them to existing records when appropriate, and investigate duplicates before removing anything.
Don’t delete reconciled entries without understanding how the correction affects your books.
6. Failing to Track Unpaid Invoices
A sale doesn’t always mean you’ve collected the money.
If customer invoices sit unpaid for weeks, your business may struggle to cover payroll, rent, or supplier bills.
Late collections can be particularly challenging for service businesses and contractors.
How to fix it: Review accounts receivable regularly, monitor overdue invoices, and establish consistent payment reminders.
Clear payment terms, deposits, and milestone billing may also help reduce collection delays.
7. Overlooking Inventory and Cost of Goods Sold
For retail and e-commerce businesses, inventory mistakes can significantly distort financial results.
If your records don’t reflect purchases, returns, damaged goods, and inventory sold, you may misunderstand both profitability and available stock.
How to fix it: Track inventory movements and reconcile physical quantities with recorded balances.
Use a consistent inventory accounting method appropriate for your business.
Federal tax rules generally require inventory accounting when merchandise is an income-producing factor, although eligible small businesses may use permitted alternatives.
8. Treating Sales Tax and Payroll Withholding as Revenue
Some money passing through your bank account belongs to someone else.
Sales tax collected from customers and payroll taxes withheld from employees can represent liabilities owed to tax authorities.
Treating those amounts as spendable business income can create cash shortages when payments become due.
How to fix it: Record applicable tax liabilities separately, reconcile them to supporting reports, and monitor filing and payment deadlines.
Sales tax, payroll, and withholding requirements depend on your jurisdiction and business activities.
Good bookkeeping makes it easier to identify errors before they become bigger problems. See how IntegriBooks can help keep your business records organized and accurate.
9. Losing Receipts and Financial Records
A bank transaction alone may not establish what was purchased or whether an expense qualifies for a deduction.
Without supporting records, it’s harder to verify expenses, resolve disputes, or prepare tax returns.
How to fix it: Store invoices, receipts, contracts, and supporting documents in an organized digital or physical system.
Keep records for as long as needed under applicable requirements. There is no universal three-year rule for every document; employment tax and property-related records can require longer retention.
10. Waiting Until Tax Season to Review Your Books
This is among the most avoidable bookkeeping mistakes small business owners make.
When transactions go unchecked for months, even a small error can become difficult to trace.
You may spend hours searching for missing information or pay for extensive cleanup work.
How to fix it: Establish a monthly bookkeeping routine that includes reconciliation, transaction reviews, invoice follow-ups, expense checks, and financial reporting.
Catching errors early usually makes them easier to investigate.
How to Fix Bookkeeping Errors in a Small Business
Already dealing with inaccurate records? Start with a structured review.
- Identify the problem. Compare bookkeeping records with bank statements, invoices, receipts, and other reliable documents.
- Determine the affected period. Check whether the error involves one transaction or several months.
- Correct the entry properly. Use the appropriate correction, matching, or adjusting-entry process while preserving an audit trail.
- Reconcile affected accounts. Confirm that corrections haven’t created new differences.
- Review the financial impact. Check whether income, expenses, liabilities, cash flow, or previously filed returns were affected.
Avoid changing prior-year or tax-sensitive entries without professional guidance. Some corrections may require amended returns or other formal adjustments.
Does Your Business Type Affect Your Bookkeeping?
Absolutely. Different businesses face different risks.
| Business type | Common bookkeeping challenges |
|---|---|
| Retail and e-commerce | Inventory, returns, marketplace fees, sales tax |
| Freelancers and consultants | Invoices, client payments, project expenses |
| Restaurants and cafés | Daily sales, tips, food costs, payroll |
| Construction and home services | Job costing, deposits, materials, progress billing |
| Subscription businesses | Recurring payments, cancellations, deferred revenue where applicable |
Your bookkeeping process should reflect how your business operates—not simply copy another company’s system.
QuickBooks, Excel, or Another Tool: Which Is Better?
The right tool depends on your transaction volume, business complexity, and reporting needs.
QuickBooks and similar accounting platforms can offer bank feeds, invoicing, reconciliation, and financial reporting, depending on the product and plan.
Excel can support straightforward bookkeeping, but manual entry, formulas, and file management require careful controls.
Neither option guarantees accurate books.
The important questions are whether your transactions are recorded correctly, your accounts are reconciled, and your reports reflect the business’s actual financial position.
FAQs About Small Business Bookkeeping Mistakes
What is the most common bookkeeping mistake?
Mixing personal and business transactions, skipping reconciliation, and miscategorizing expenses recur. The most damaging mistake depends on the business.
How often should small businesses review their books?
Monthly reconciliation is a practical baseline. Businesses with frequent transactions, tight cash flow, or substantial inventory may need more frequent reviews.
Can bookkeeping mistakes affect taxes?
Yes. Incorrect income, expense, payroll, or inventory records can affect tax calculations and reporting. The consequences depend on the error and applicable rules.
Can accounting software fix bookkeeping errors automatically?
Some tools can flag potential duplicates, categorize transactions, or identify discrepancies. However, automated suggestions still need review, and software can’t detect every accounting error.
Final Thoughts: Accurate Books Help Protect Your Business
Bookkeeping isn’t just about preparing for tax season.
It helps you understand where money is going, what customers owe, which expenses are increasing, and whether your business can comfortably meet its obligations.
Small mistakes are easier to manage when you catch them early.
A consistent bookkeeping routine, reliable records, and occasional professional review can help prevent minor errors from becoming expensive problems.
Want to spend less time fixing bookkeeping mistakes and more time running your business? Visit IntegriBooks to learn how professional bookkeeping support can help you maintain clearer, more reliable financial records.