
Tax season sneaks up on small-business owners. One minute, you’re focused on customers, expenses, and keeping everything running. The next, you’re gathering receipts and wondering whether you’ve set aside enough money for taxes.
But here’s something to understand: tax planning and tax preparation aren’t the same.
Both play an important role in managing your business finances, but they serve different purposes. Knowing how they work can help you avoid unnecessary surprises and make more informed financial decisions throughout the year.
Let’s break down the differences.
Affiliate Disclosure: This article contains affiliate links. If you join Wealthy Affiliate through one of my links, I may earn a commission at no additional cost to you. I recommend only products and services I have personally used or genuinely believe will add value for my readers. All opinions expressed in this review are my own.
What Is Tax Preparation?
Tax preparation is the process of organizing financial information, completing tax returns, and filing the required forms with tax authorities.
It generally focuses on what happened during a completed tax year.
For a small business, tax preparation may involve:
- Gathering income and expense records
- Reviewing financial statements and supporting documents
- Reporting business income and eligible deductions
- Calculating tax liability or an available refund
- Completing federal and applicable state tax returns
- Filing returns by the required deadlines
For example, a freelance graphic designer might collect client payment records, software expenses, and other business documents to prepare a federal income tax return.
Tax preparation helps ensure the business reports its financial activity accurately and meets its filing obligations.
Although much of this work happens during filing season, preparation can begin earlier. Tax professionals may also identify issues or provide advice while preparing returns.
What Is Tax Planning?
Tax planning is the process of reviewing your financial situation and evaluating decisions that may affect your current or future taxes.
Instead of concentrating only on what has already happened, tax planning looks ahead.
For small-business owners, this might include:
- Reviewing projected business profits
- Adjusting estimated tax payments when necessary
- Evaluating retirement contribution options
- Considering the tax treatment of equipment purchases
- Reviewing available deductions and credits
- Discussing business tax classification and compensation
- Preparing for changes in income or business operations
Imagine a bakery owner expecting significantly higher profits this year.
Instead of waiting until filing season, the owner meets with a tax professional to estimate potential taxes, review planned equipment purchases, and decide whether to adjust estimated payments.
The goal isn’t necessarily to pay the lowest possible tax at any cost. It’s to make decisions that support the business while complying with applicable tax rules.
Tax Planning vs. Tax Preparation: Key Differences
| Main purpose | Report and file taxes accurately | Evaluate future tax decisions |
| Timing | Primarily during and after the tax year | Throughout the year |
| Focus | Past financial activity | Current and future financial choices |
| Common tasks | Review records, calculate taxes, file returns | Estimate taxes, review strategies, evaluate options |
| Main benefit | Helps meet filing obligations | Helps anticipate liabilities and make informed decisions |
The simplest way to remember the difference is this:
Tax preparation tells the IRS what happened. Tax planning helps you decide what to do next.
The two services can overlap. A qualified tax professional may provide both, and information discovered during return preparation can lead to better planning for the following year.
Examples of Tax Preparation for Small Businesses
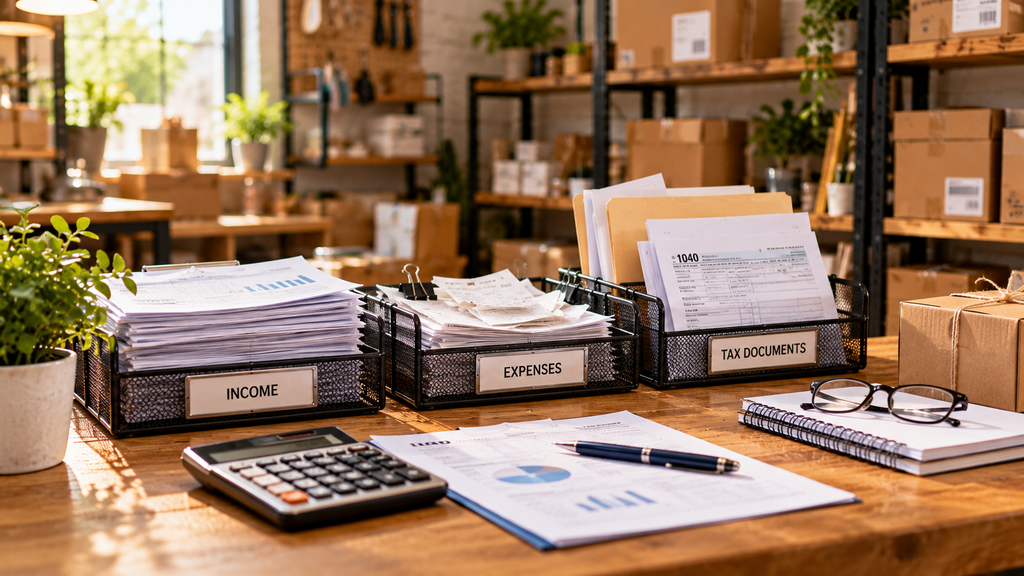
Let’s say you operate a small online store.
During tax preparation, you or your preparer might:
- Review sales and payment processor records.
- Reconcile business income and expenses.
- Account for inventory and cost of goods sold, where applicable.
- Review eligible deductions.
- Prepare the appropriate business tax forms.
- Check the completed return before filing.
The emphasis is on accurately reporting the business’s activity under the tax rules for that year.
Even when you hire a professional, you’re responsible for reviewing your return and providing complete, accurate information.
Examples of Tax Planning for Small Businesses
Now imagine the same online store is growing.
Sales have increased, you’re considering hiring employees, and you may need additional storage equipment.
Tax planning could involve discussing whether to:
- Update estimated tax payments based on projected income.
- Review equipment depreciation options before purchasing
- Establish an eligible retirement plan.
- Evaluate payroll and employee benefit obligations.
- Review whether the current tax classification still fits the business.
These decisions involve more than taxes. They can affect cash flow, operating costs, and long-term business plans.
For example, an LLC is a legal business structure, while S corporation status is a federal tax classification available to eligible entities. Choosing an S corporation election requires meeting certain requirements and involves administrative costs, including paying reasonable compensation to shareholder-employees who provide services.
It isn’t automatically the better choice for every business.
When Should You Start Tax Planning?
Ideally, before you face an important financial decision—not just when tax season begins.
A practical approach is to review your tax situation at least periodically, particularly when:
- Business income changes significantly.
- You hire employees or contractors.
- You’re considering a major purchase.
- You change how your business operates.
- You plan retirement contributions.
- Tax laws affecting your business change
Some decisions must be completed by year-end to affect that year’s taxes. Others have deadlines before or after December 31.
That’s why checking the rules for your specific situation matters more than following a generic year-end checklist.
Why Good Bookkeeping Matters for Both
Neither tax planning nor tax preparation works particularly well with incomplete financial records.
If your bookkeeping is several months behind, it becomes harder to estimate profits, identify eligible expenses, or determine how much money your business may need for taxes.
Accurate bookkeeping helps you:
- Track income and expenses consistently
- Keep business and personal transactions separate.
- Reconcile bank and credit card accounts.
- Maintain records supporting deductions.
- Review financial performance during the year.
- Provide reliable information to your tax professional.
Think of bookkeeping as the foundation. Tax preparation uses those records to report financial activity, while tax planning uses them to help evaluate future decisions.
Need help keeping your business records organized? Visit IntegriBooks to learn how consistent bookkeeping can support better financial decisions and a smoother tax season.
Do You Need Both Tax Planning and Tax Preparation?
For many small businesses, the answer is yes.
Tax preparation helps you meet filing requirements. Tax planning can help you anticipate obligations and evaluate opportunities before deadlines pass.
However, the level of support you need depends on your circumstances.
A small business with straightforward finances may need occasional planning conversations. A growing company with employees, inventory, or multiple income streams may benefit from more frequent reviews.
You don’t necessarily need separate professionals for each service. Some CPAs, enrolled agents, and other qualified tax professionals offer both.
Focus on understanding which services you’re receiving, rather than assuming tax return preparation automatically includes year-round planning.
How to Choose the Right Tax Professional
Before hiring someone, ask a few practical questions:
- Do you provide tax planning, tax preparation, or both?
- Do you have experience with businesses like mine?
- How often can we review my financial situation?
- How do you charge for planning and preparation?
- What records will you need?
- What credentials and IRS representation rights do you have?
Paid federal tax return preparers generally must have a valid Preparer Tax Identification Number (PTIN). Credentials and representation rights differ, so verify the professional’s qualifications.
Look for someone who explains your options clearly and doesn’t promise guaranteed refunds or tax savings.
Frequently Asked Questions
Is tax planning the same as tax preparation?
No. Tax preparation focuses primarily on accurately completing and filing returns. Tax planning evaluates decisions that may affect taxes before or after filing.
Can tax software handle both?
Tax software can help prepare returns, and some products offer estimates, planning tools, or professional assistance. However, capabilities vary, and complex business decisions may benefit from individualized professional advice.
Does tax planning always save money?
No. Tax planning can identify legitimate tax-saving opportunities, but it doesn’t guarantee savings. It can also improve cash-flow forecasts, manage payment obligations, and help you avoid preventable surprises.
Is tax planning only useful at year-end?
No. Year-end reviews can be valuable, but planning throughout the year gives you more opportunities to respond to financial changes and applicable deadlines.
Can a bookkeeper replace a tax professional?
Not necessarily. Bookkeeping focuses on recording and organizing financial activity. Tax planning, return preparation, and representation require different expertise. The services often complement one another.
Final Thoughts
Tax planning and tax preparation work best together.
Preparation helps you report what happened. Planning helps you evaluate what comes next.
And both become easier when your financial records are accurate, organized, and available when you need them.
You don’t have to turn every business decision into a tax strategy. But understanding the difference can help you ask better questions and avoid leaving important decisions until the last minute.
Better tax decisions begin with better financial records. Explore IntegriBooks to see how dependable bookkeeping can keep your business prepared year-round.
Disclaimer: This article provides general U.S. tax information for educational purposes and is not individualized tax, accounting, or legal advice. Federal and state requirements vary. Consult an appropriately qualified professional about your circumstances.