Tax software is good at calculating what you enter. It is much less effective at deciding whether an expense qualifies, identifying what you forgot, or explaining how today’s deduction affects future tax years.
That distinction matters. A legitimate business expense generally must be both ordinary for your field and necessary for your business. But the software cannot prove the business purpose, reconstruct missing mileage logs, or decide whether an aggressive position fits your facts.
Here is what small-business owners should review before relying on software to file a 2026 federal return.
Note: This article covers general U.S. federal tax information for the 2026 tax year. State rules may differ, and individual circumstances matter. It is not individualized tax advice.
Affiliate Disclosure: This article may contain affiliate links. If you make a purchase through one of these links, I may earn a commission at no additional cost to you. I identify products I have personally used where relevant. I may also recommend products based on independent research, and I aim to explain the basis for each recommendation. All opinions are my own.
1. Your LLC label does not determine your federal tax treatment
“LLC” is a legal form, not a complete federal tax classification. Depending on its owners and elections, an LLC may be treated as a disregarded entity, partnership, C corporation, or S corporation.
Tax software needs the correct classification before it can ask the right questions or put deductions on the right return. It also may not explain reimbursement issues. For example, an owner-employee of an S corporation generally should not treat personally paid company expenses as Schedule C expenses. A properly documented reimbursement arrangement may be more appropriate.
Confirm how the business is taxed—not just what appears in its legal name—before entering expenses. The IRS explains the default and elective classifications in its LLC filing guidance.
2. Software cannot deduct expenses you never recorded
Bank and credit card imports are convenient, but they don’t capture the full picture. Cash purchases, charges on a personal card, payment-app fees, subscriptions, insurance, professional dues, and small equipment purchases can be missed.
Imports can also misclassify transfers, loan payments, owner draws, personal purchases, and income. Review every category and reconcile the totals to the underlying accounts. A deduction is not safer merely because an algorithm suggested it.
The IRS maintains a guide to business-expense resources covering common categories and recordkeeping.
Want a simpler way to catch missed write-offs? Use our step-by-step checklist to organize expenses, verify documentation, and review common deduction categories before you file.
Review the Business Deduction Checklist →
3. Mixed personal and business costs require allocation
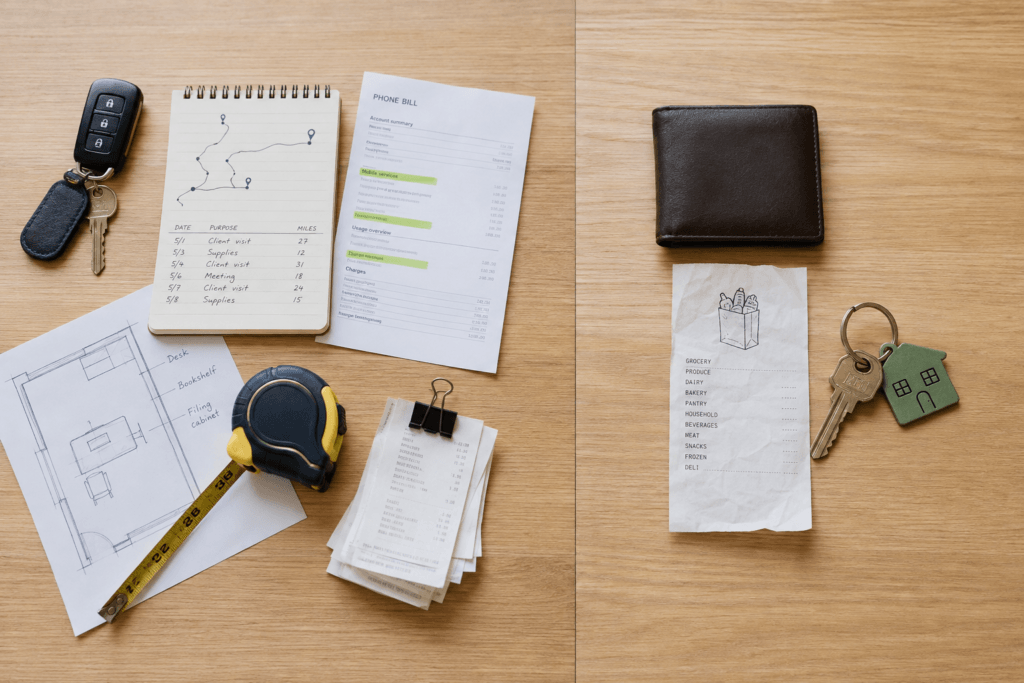
A phone, internet plan, vehicle, or trip may serve both business and personal purposes. Usually, only the business portion is deductible, and you should allocate it reasonably and support it with records.
For vehicles, taxpayers may use the optional standard mileage method when eligible or calculate actual expenses. The 2026 business mileage rate is 72.5 cents per mile. For an owned vehicle, you generally must begin the standard mileage method in the first year the vehicle is available for business use; special consistency rules apply to leased vehicles. Commuting is generally personal, not business mileage. See the IRS 2026 mileage-rate announcement and Publication 463 for details.
4. A home-office calculator does not determine eligibility
For most self-employed taxpayers, the space must be used regularly and exclusively for business, subject to specific exceptions. A kitchen table used by the household generally does not satisfy the exclusive-use test.
Eligible taxpayers can compare two methods:
- The simplified option uses $5 per square foot, up to 300 square feet.
- The regular method allocates qualifying actual expenses and may include depreciation.
The regular method can create recordkeeping and future depreciation recapture consequences. The simplified method does not allow carrying over a deduction limited by business income, while the regular method may. Software can run the arithmetic, but it cannot decide which method is better without accurate inputs and a view of future years. Review the IRS home-office comparison for more information.
5. Startup costs are not the same as current operating expenses
Expenses incurred before a business begins operations may be startup or organizational costs rather than ordinary current-year expenses. The timing of when the business actually begins matters, as does the type of cost.
Don’t put every pre-opening payment into “legal fees,” “advertising,” or another current expense category just because the software lets you. Some costs may qualify for a limited immediate deduction, with the remainder amortized; others follow different capitalization rules. Keep pre-opening records separate and review them when the business becomes active.
6. Faster depreciation is not automatically the best choice
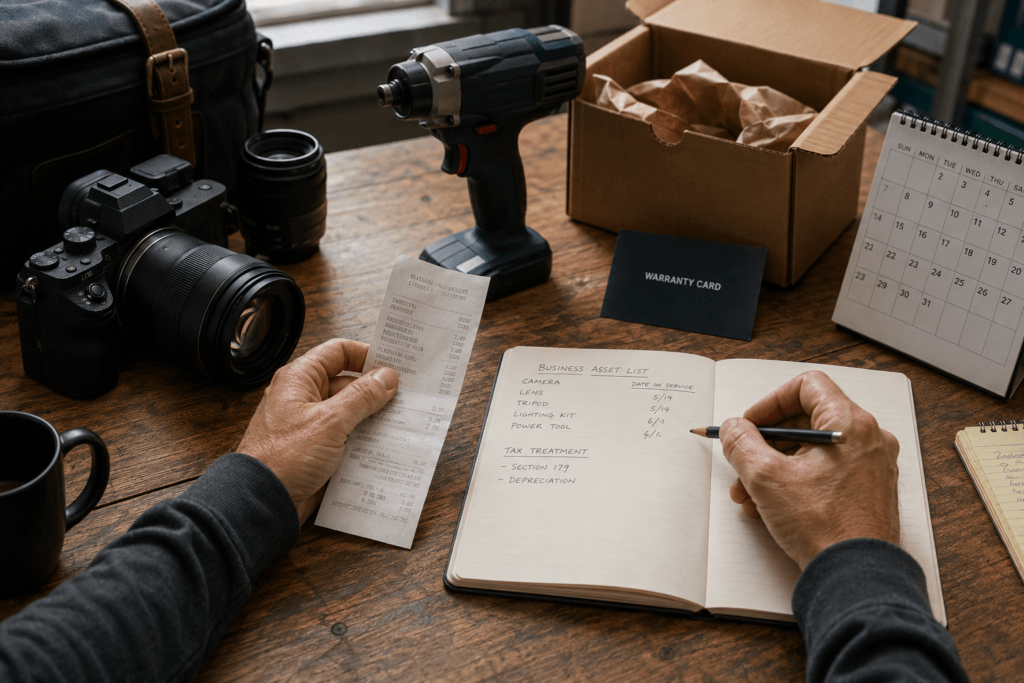
Section 179, bonus depreciation, and regular depreciation can produce very different timing results. For eligible property acquired after January 19, 2025, current law generally provides permanent 100% bonus depreciation, but eligibility, acquisition dates, placed-in-service dates, business-use rules, vehicle limits, and elections still matter. The IRS summarizes the current rule in Notice 2026-11.
Taking the largest deduction now is not always optimal. A business expecting higher taxable income later may benefit from preserving deductions. Section 179 also has limitations, and some deductions may be recaptured if business use later declines. Major asset purchases deserve a multi-year comparison, not just acceptance of the software default.
7. Meals and entertainment are easy to confuse
Most qualifying business meals are generally subject to a 50% limit. Entertainment expenses are generally nondeductible unless a specific exception applies. To be considered under the meal rules, food and beverages purchased at an entertainment event should be stated separately from the entertainment cost.
Exceptions to the 50% meal limit include certain employee recreational events. Do not assume every “team meal” is 100% deductible or that a client outing becomes deductible merely because business was discussed. The IRS details the rules and exceptions in Publication 463.
8. Inventory and cost of goods sold are not ordinary write-offs
Businesses that sell products must distinguish inventory and cost of goods sold from operating expenses. Purchases are not always deductible when paid. Returns, allowances, damaged inventory, materials, freight, and changes in ending inventory can affect the calculation.
A tax interview may ask for a single cost-of-goods-sold total without explaining how to build it. Reconcile beginning inventory, purchases, production costs when applicable, and ending inventory before entering the number.
A practical review before filing
Before submitting a return, ask:
- Is the business’s federal tax classification correct?
- Are all accounts reconciled, including personal accounts used for business?
- Is there documentation for the amount, date, business purpose, and business-use percentage?
- Were startup costs, assets, inventory, loan payments, and owner transactions classified correctly?
- Were mileage, meals, travel, and home-office claims tested against the specific rules?
- Were depreciation choices compared across more than one tax year?
- Does the return agree with payroll, sales-tax filings, information returns, and the books?
Want to verify a deduction before you claim it? Start with the IRS directory for rules covering common business expenses, recordkeeping, depreciation, and employee costs.
Explore IRS Business-Expense Resources →
The bottom line
Tax software is a filing tool, not a substitute for clean records or professional judgment. Its biggest blind spot is context: it cannot know what you omitted, whether your documentation is adequate, or which legal choice best fits your long-term tax picture.
Use the software to calculate and file. Use your records—and, when the facts are complex, a qualified tax professional—to decide what belongs on the return.